SEBI Changes Mutual Fund Investment Rules From November 1: What SIP Investors Need to Know

Millions of Indians invest in mutual funds through Systematic Investment Plans (SIPs), but many may not realise that the plan they select can affect their long-term investment costs.
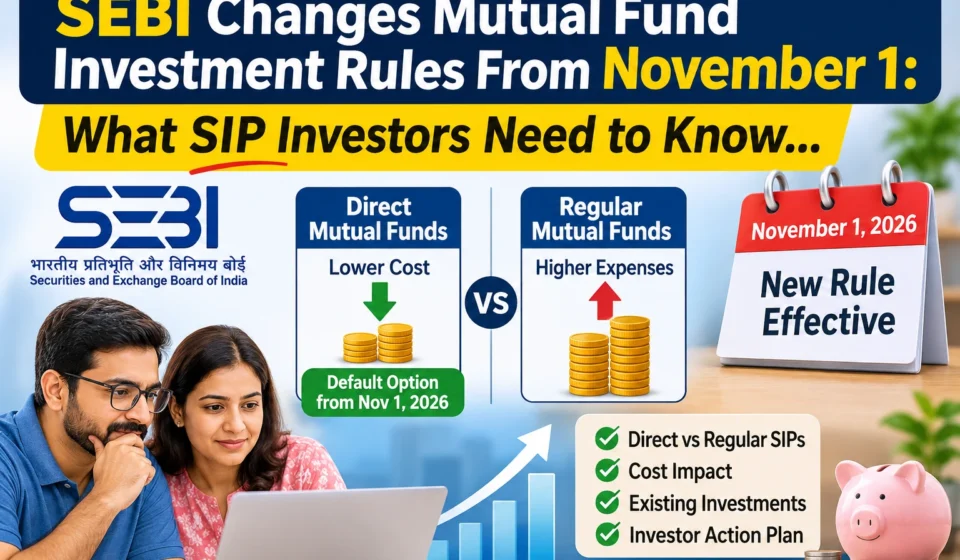
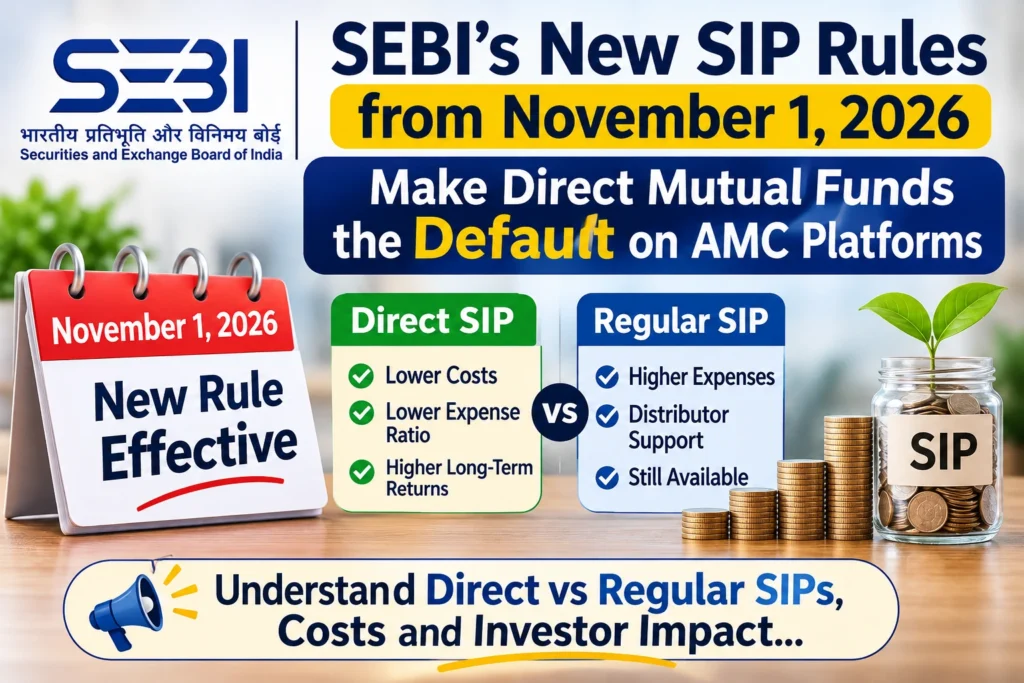
Starting November 1, 2026, the Securities and Exchange Board of India (SEBI) has introduced an important change to how mutual funds are presented to investors on Asset Management Companies’ (AMCs) digital platforms.
Direct mutual fund plans will now be the default option on AMC websites and apps. Investors choosing regular plans must be informed that these plans carry higher expense ratios.
The change aims to improve transparency and help investors understand the cost of investing before making a decision.
But does this mean regular SIP investments will become more expensive? Will existing investors have to change their SIPs? And should investors move their investments from regular to direct plans?
Here is what mutual fund investors need to understand.
1. What Is the New SEBI Rule for SIP Investments?
SEBI Chairman Tuhin Kanta Pandey announced the change at the NDTV Profit Ignite event in October 2026.
Under the new arrangement:
- Direct mutual fund plans will be the default selection on AMC digital platforms from November 1, 2026.
- Investors who select regular plans must be informed about their higher expense ratios.
- Regular mutual fund plans will continue to remain available.
- Investors can still choose to invest through mutual fund distributors.
The change is intended to make investors more aware of the cost difference between direct and regular mutual fund plans.
Importantly, this is a change in the default selection and disclosure process, not a ban on regular mutual fund investments.
2. Direct vs Regular Mutual Funds: What Is the Difference?
Both direct and regular mutual fund plans invest in the same underlying portfolio and are managed by the same fund manager.
The primary difference is the distribution channel and the expense ratio.
| Feature | Direct Plan | Regular Plan |
|---|---|---|
| Investment channel | Directly through AMC or eligible direct platforms | Through distributors or intermediaries |
| Fund portfolio | Same | Same |
| Fund manager | Same | Same |
| Expense ratio | Lower | Generally higher |
| Distributor commission | Not included | Included in applicable distribution expenses |
| Investor guidance | Self-managed or separately arranged | Distributor assistance may be available |
| NAV | Separate | Separate |
Direct plans generally have lower expense ratios because they do not include distributor commissions.
Regular plans have higher expenses because distribution-related costs are included.
Over an extended investment period, even a relatively small difference in expenses can affect the final investment corpus.
3. How Much Can You Save With a Direct SIP?
The biggest advantage of direct mutual fund plans is their potentially lower investment cost.
Consider an investor investing ₹10,000 every month through an SIP for 15 years.
For illustration, assume:
- Monthly investment: ₹10,000
- Investment period: 15 years
- Illustrative annual return after expenses in a regular plan: 11%
- Illustrative annual return after expenses in a direct plan: 11.5%
These are hypothetical assumptions, not actual fund returns or guaranteed future performance.
| Particulars | Regular SIP | Direct SIP |
|---|---|---|
| Monthly investment | ₹10,000 | ₹10,000 |
| Investment duration | 15 years | 15 years |
| Total investment | ₹18 lakh | ₹18 lakh |
| Assumed annual return | 11% | 11.5% |
| Estimated final value | ₹45.9 lakh | ₹48 lakh |
| Difference | Approximately ₹2.1 lakh |
Illustrative SIP calculations assume monthly investments at the end of each month and constant annualised returns compounded monthly. Actual outcomes will vary.
This example demonstrates how differences in investment costs can influence long-term wealth creation.
However, choosing a direct plan does not guarantee better fund performance or eliminate market risk.
4. Will Existing Regular SIP Investments Automatically Become Direct SIPs?
No.
This is one of the most important things existing mutual fund investors should understand.
The November 1 change does not automatically convert existing regular mutual fund investments or SIP registrations into direct plans.
If you are already investing ₹5,000, ₹10,000 or ₹20,000 every month through a regular SIP, your existing investment arrangement does not automatically change because of this announcement.
You can continue with your existing regular SIP.
However, investors who want to move from regular to direct plans must understand that this is generally treated as a switch involving redemption from one plan and investment into another.
Such a switch may involve:
- Capital gains tax implications.
- Applicable exit loads.
- Changes in investment records and folio arrangements.
- A need to review the suitability of the investment.
Investors should calculate these costs before making any changes.
5. Can You Still Invest in Regular Mutual Fund SIPs?
Yes.
SEBI has not discontinued regular mutual fund plans.
Investors who prefer professional assistance from mutual fund distributors can continue choosing regular plans.
The main change is that investors will have greater visibility into the additional expenses associated with regular plans.
For example:
An investor visiting an AMC website to start a new SIP may see the direct plan selected by default.
If the investor prefers a regular plan, they can still select it after being informed about its higher expense ratio.
This gives investors more visibility and control over their investment decisions.
6. Which Is Better: Direct SIP or Regular SIP?
There is no single answer for every investor.
The right option depends on financial knowledge, investment experience and the level of guidance required.
Direct SIP may suit investors who:
- Understand mutual fund categories and investment risks.
- Can independently research and compare mutual funds.
- Know how to assess expense ratios and fund performance.
- Can monitor their portfolio and rebalance when required.
- Prefer managing investments independently.
Regular SIP may suit investors who:
- Are new to mutual fund investing.
- Need help selecting suitable mutual funds.
- Prefer assistance with portfolio reviews.
- Want ongoing support from a mutual fund distributor.
- Are uncomfortable managing investments independently.
The additional cost of a regular plan should be evaluated against the actual value of the guidance and services received.
A lower expense ratio alone should not be the only factor when selecting a mutual fund.
7. What Should Existing SIP Investors Do Now?
The new SEBI arrangement is a good opportunity for investors to review their mutual fund portfolios.
Before changing an existing SIP, consider these five steps:
Step 1: Check your existing mutual fund plan
Log in to your mutual fund account and identify whether your investments are in direct or regular plans.
Step 2: Compare expense ratios
Check the direct and regular expense ratios of the same mutual fund scheme.
Step 3: Evaluate distributor services
If you are paying additional expenses through a regular plan, understand what guidance and support you receive in return.
Step 4: Calculate switching costs
Before moving to a direct plan, check applicable exit loads and potential capital gains tax.
Step 5: Avoid making decisions based only on lower expenses
Fund suitability, investment objectives, risk tolerance and asset allocation remain important.
Investors should avoid hurriedly switching their entire portfolios simply because direct plans have become the default option.
8. Does the New SEBI Rule Affect All Investment Platforms?
The announcement specifically refers to the digital platforms of Asset Management Companies.
Investors should not assume that every third-party investment platform, brokerage app or distributor platform will follow the same default-selection arrangement.
The applicable investment channel and plan type should always be checked before completing a transaction.
Also, the new arrangement does not change the underlying investment objective or portfolio of a mutual fund scheme.
Frequently Asked Questions (FAQs)
Q1. What is the new SEBI SIP rule from November 1, 2026?
SEBI has made direct mutual fund plans the default option on AMC digital platforms from November 1, 2026. Investors choosing regular plans must be informed about their higher expense ratios.
Q2. Has SEBI banned regular mutual fund SIPs?
No. Regular mutual fund plans are still available. Investors can continue investing through distributors and intermediaries.
Q3. Will my existing regular SIP automatically become a direct SIP?
No. Existing regular SIPs will not automatically convert into direct plans under this change.
Q4. Why are direct mutual fund plans cheaper?
Direct plans do not include distributor commissions in their expense structure, resulting in generally lower expense ratios than corresponding regular plans.
Q5. Can I switch from a regular mutual fund to a direct mutual fund?
Yes. Investors can generally switch between regular and direct plans of the same scheme, subject to applicable procedures, taxes and exit loads.
Q6. Do direct mutual funds offer higher returns?
Direct plans generally have lower expenses, which can contribute to higher net returns compared with the corresponding regular plan. However, actual returns depend on fund performance and market conditions.
Q7. Should beginners choose direct or regular SIPs?
Beginners who need help selecting and monitoring mutual funds may find regular plans useful. Investors comfortable managing their own portfolios may consider direct plans.
Final Takeaway
SEBI’s new mutual fund arrangement from November 1, 2026, puts investment costs in greater focus.
For investors starting new SIPs, the default selection of direct plans means they will be exposed to a lower-cost investment option when using AMC digital platforms.
However, regular plans are not being discontinued, and existing SIP investors do not need to panic or automatically switch their investments.
The bigger lesson is that investors should understand where their money is invested, how much they are paying in expenses and whether they are receiving adequate value for those costs.
Before starting your next SIP, compare direct and regular plans. A small difference in annual expenses can make a meaningful difference to long-term wealth creation.
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully and consult a qualified financial adviser before making investment decisions.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.