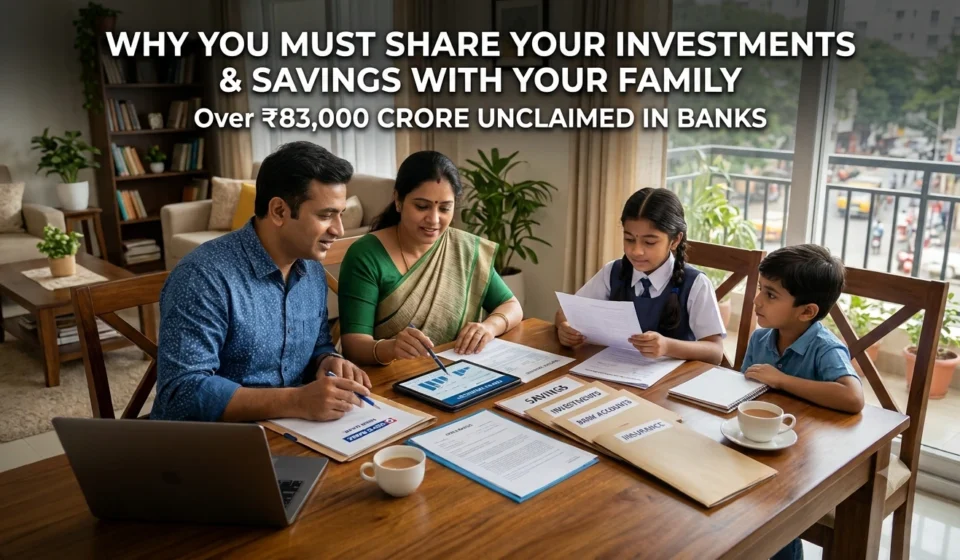
Why You Must Share Your Investments and Savings With Your Spouse and Kids: Over ₹83,000 Crore Sits Unclaimed in Banks Alone

By Shuchi, FinanceChecks.com | Published 10 November 2026 | Category: Personal Finance | Reading time: about 6 minutes
If you died suddenly tomorrow, could your family find every bank account, fixed deposit, insurance policy, mutual fund and demat account you hold? For most Indian families the honest answer is no. Money does not disappear when someone dies, but it can become very hard to find, and many families never find it. This article explains why sharing your financial details matters, what the numbers show, what exactly to share, and a simple 30-minute plan to do it this week.
Quick Answer
Sharing your investments and savings with your spouse or adult children lets them find assets, claim them faster and avoid losing money. India has a very large pile of forgotten money: unclaimed bank deposits under the RBI’s framework were reported at about ₹83,000 crore by February 2026, with about ₹8,974 crore in unclaimed insurance and about ₹3,749 crore in unclaimed mutual funds, according to figures given to Parliament. Common reasons include missing nominee details and family members not knowing the accounts exist. Make a simple list of every account with its location, nominee and contact, keep it somewhere safe, tell a trusted family member where it is, and make a will.
About This Guide
This article is written by the editorial desk of FinanceChecks.com, an independent Indian personal finance publication. Figures come from RBI and Finance Ministry data as reported in 2024 to 2026, and from public information on the UDGAM, Bima Bharosa and MITRA portals. Figures from different sources vary, since they cover different dates and definitions. Succession and nomination rules differ by asset and by religion, and this article is general information, not legal advice. Please consult a lawyer for your own situation.
What the Numbers Show
| Asset | Reported unclaimed amount | Source and date |
|---|---|---|
| Bank deposits (RBI framework) | About ₹83,000 crore | Reported by February 2026, up from about ₹74,600 crore in March 2025 |
| Bank deposits, public sector banks (DEA Fund) | ₹60,518 crore | Finance Ministry, as of January 2026 |
| Life insurance | About ₹8,974 crore | Finance Ministry, end of February 2026 |
| Mutual funds | About ₹3,749 crore | Finance Ministry, end of February 2026 |
| Shares and dividends (IEPF) | About ₹89,000 crore | Reported across 1,671 listed companies in November 2025 |
Different outlets quote different totals, from ₹1.1 lakh crore to ₹2.2 lakh crore, depending on what they include. The point is the same: a large amount of family money sits unclaimed.
Banks transfer deposits that have been unclaimed for 10 years or more to the RBI’s Depositor Education and Awareness Fund. The money still belongs to you or your heirs and can be claimed from the bank, but only if someone knows it exists.
Why Sharing Matters: Seven Reasons
1. Your family cannot claim what it cannot find. A spouse or child may know about the savings account but not the second bank’s fixed deposit, the old insurance policy or the demat account opened ten years ago.
2. Time costs money. While a claim is pending, EMIs, school fees and household bills continue. Knowing exactly where money is and who the nominee is shortens the process.
3. Missing nominee details block claims. Missing nominees are one of the common reasons assets go unclaimed. Without a nominee, legal heirs can still claim, but they may need more documents, such as a succession certificate or legal heir certificate, and more time.
4. A nominee is not always the final owner. Under the usual rule, a nominee receives the money to hold on behalf of the legal heirs, and the law of succession or your will decides who finally gets it. Insurance has its own rules, and a close relative who is a nominee can be treated as the beneficiary. Confusion here causes family disputes, so it is worth getting right.
5. Online accounts are hard to open without access. Net banking, UPI, mutual fund and demat accounts are all protected by passwords, OTPs and phone numbers. Without a plan, even a rightful heir can struggle.
6. Debts and liabilities need to be known too. Loans, credit card dues and guarantees given to others affect the estate. A family that does not know about them can face unwelcome surprises.
7. It protects relationships. Silence about money leads to suspicion and arguments. A shared list and a clear will prevent most of them.
What to Share: The Family Finance List
Write these down in a simple document or sheet. Keep it factual.
| Category | What to list |
|---|---|
| Bank accounts | Bank, branch, account type, and nominee, including joint holders |
| Fixed and recurring deposits | Bank, amount, maturity date, receipt location |
| Insurance | Life, health, term and vehicle policies, with insurer, policy number, nominee and premium due date |
| Mutual funds and SIPs | Fund house, folio numbers, platform (for example, a registrar or app) |
| Shares | Demat account, broker, depository, and nominee |
| Retirement | EPF or UAN, NPS PRAN, PPF and pension accounts |
| Property | Papers, location, loans against it |
| Gold, silver and valuables | What you own, where it is kept, locker details |
| Loans and liabilities | Lender, amount, EMI, and any guarantees you gave |
| Other | Business interests, money owed to you, digital assets |
| People | Your CA, lawyer, bank contact, insurance agent and a trusted friend or relative |
How to Share Safely
Sharing does not mean handing over every password to everyone.
- Keep the list, not the passwords, in the open. Write what exists and where, and keep access details separately.
- Use a safe place. A locker, a sealed envelope with a trusted person or a password manager with an emergency-access feature are options. Tell one person where it is.
- Do not share OTPs or PINs with anyone, including family, on an ongoing basis. Scammers often target families who are careless with these.
- Keep the list updated. Review it every year, perhaps on a birthday or at the start of the financial year.
- Make sure phone numbers and emails on accounts are current, so alerts and claim communication reach the right person.
Legal Basics Every Family Should Cover
- Nominate on every account. Banks now allow up to four nominees on an account under the Banking Laws (Amendment) Act, 2025. Mutual funds, demat accounts, insurance, EPF and NPS also have nomination options. Check each one and name nominees you actually intend.
- Make a will. A simple, properly signed and witnessed will lets you decide who gets what and avoids disputes. Register it if you wish. This is the strongest step you can take.
- Use joint holders carefully. A joint account with “either or survivor” can help access, but it can also have legal and tax consequences. Ask your bank and a lawyer.
- Know the claim route. Banks, insurers and fund houses each have a death claim process with a form, a death certificate, identity proof and sometimes a succession certificate.
- Check for forgotten money. Look up bank deposits on the RBI’s UDGAM portal (udgam.rbi.org.in), insurance on IRDAI’s Bima Bharosa portal, mutual funds through SEBI’s MITRA via MF Central, and shares and dividends on the IEPF site. A government portal for unclaimed financial assets was also reported to have launched on 29 May 2026.
A 30-Minute Family Money Meeting
You can do this over one evening.
- Minutes 0 to 5: Explain why you are doing this. Say it is about being prepared, not about anyone leaving.
- Minutes 5 to 15: Walk through the list above and note what exists and where.
- Minutes 15 to 20: Check nominees on the big accounts, and note who needs to be added or changed.
- Minutes 20 to 25: Decide who the trusted contact is and where the list and papers will be kept.
- Minutes 25 to 30: Agree on the next steps: a will, nominee updates and a date for the next annual review.
Common Mistakes to Avoid
The usual mistakes are keeping everything in your head, using a nominee for only some accounts, naming a nominee who has since died or fallen out of touch, forgetting small accounts and old insurance policies, keeping the list where nobody can find it, not making a will because it feels morbid, and sharing passwords carelessly. Another is assuming the nominee will automatically keep the money. The law may require the nominee to share it with other heirs.
My Take
Many people avoid this topic because it feels uncomfortable. I understand that. But I have seen how much stress a clear list removes for a grieving family. It costs one evening and a notebook, and it makes a very bad time somewhat easier.
If you do one thing this week, write the list. If you do two, check your nominees. If you do three, start a will. None of this requires a lot of money. It only requires that you do it before you need to.
Frequently Asked Questions
1. Why should I tell my spouse about my investments? So they can find, claim and manage assets quickly if something happens to you. Unclaimed money in India runs into tens of thousands of crores, partly because families did not know about accounts or nominees were missing.
2. Is a nominee the owner of the money? Not always. A nominee usually receives the money on behalf of the legal heirs, and the law of succession or a will decides who finally owns it. Life insurance has its own rules for beneficiary nominees.
3. What happens if there is no nominee? Legal heirs can still claim, but may need extra documents such as a legal heir certificate or succession certificate, and the process can take longer.
4. How can I check for unclaimed money in a family member’s name? Use RBI’s UDGAM portal for bank deposits, IRDAI’s Bima Bharosa portal for insurance, SEBI’s MITRA through MF Central for mutual funds, and the IEPF site for shares and dividends.
5. Should I share my passwords with my family? Share where things are and who the contacts are, and keep access details in a secure place such as a locker, a sealed envelope or a password manager with emergency access. Never share OTPs or PINs on an ongoing basis.
Disclaimer
This article is for general information and education only. It is not legal, tax or financial advice. Succession, nomination and claim rules differ by asset type, religion and state, and can change. Figures on unclaimed assets come from reports and vary by date and definition. Consult a lawyer or chartered accountant for your own situation.
Sources Consulted
Finance Ministry replies in Parliament (March 2026) on unclaimed deposits, insurance and mutual funds, as reported by Upstox. Whalesbook report on unclaimed financial assets rising past ₹1.1 lakh crore (2026). RBI Annual Report (May 2024) as reported by Business Standard. RBI UDGAM portal FAQs. PIB press release on unclaimed financial assets. India Policy Hub and MyFinanceWisdom guides on claiming unclaimed deposits (2026). Business Standard reporting on the Banking Laws (Amendment) Act, 2025 nomination rules.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.