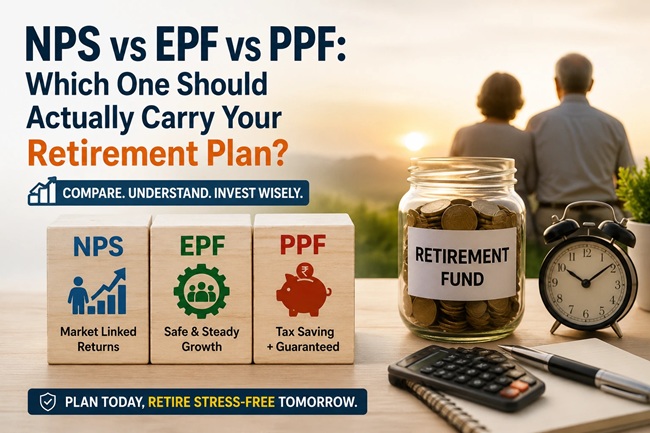
NPS vs EPF vs PPF: Which One Should Actually Carry Your Retirement Plan?

Rohit is thirty-four, has been contributing to EPF automatically since his first job, opened a PPF account on his father’s advice five years ago, and started an NPS account last year purely because his HR team mentioned it during a tax-saving webinar. He has never once sat down and asked himself whether these three accounts, quietly running in parallel, actually add up to a coherent retirement plan, or whether he’s simply been accumulating retirement products without a strategy behind them. When a colleague asked him recently which of the three he was “actually depending on” for retirement, Rohit realised he genuinely didn’t know the answer.
If you’re in a similar position, contributing to two or even all three of these without a clear sense of how they fit together, this is worth working through properly, because the honest answer isn’t “pick one.” It’s understanding what each one is actually built to do.
Quick Answer
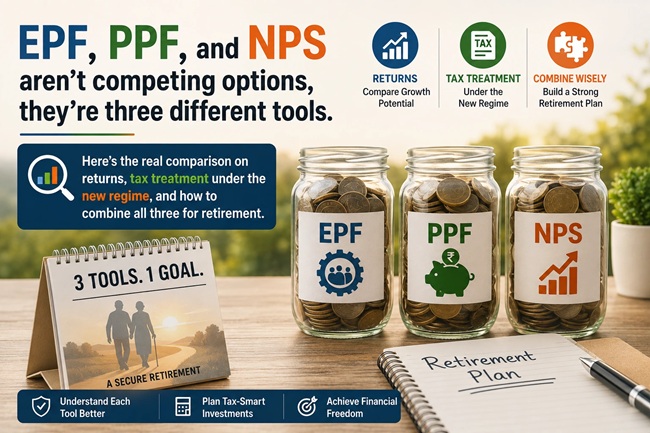
EPF, PPF, and NPS are not competing alternatives; they are three structurally different retirement tools, and for most salaried Indians, the strongest retirement plan uses two or three of them together rather than choosing just one. EPF is the mandatory, employer-matched foundation for salaried employees, currently earning 8.25 percent for FY 2025-26, fully tax-free, and effectively boosted by “free” employer contributions. PPF is a voluntary, government-guaranteed debt instrument open to everyone, including the self-employed, currently earning 7.1 percent per annum, fully tax-exempt at every stage. NPS is a market-linked retirement account regulated by PFRDA, offering exposure to equity and debt, with potentially higher long-term returns but a mandatory annuity requirement on 40 percent of the corpus at retirement. Crucially, under the new tax regime, which is now the default, most of the Section 80C and 80CCD(1B) tax benefits tied to these instruments no longer apply, except for employer contributions to NPS under Section 80CCD(2), which remains available even under the new regime, a detail that changes the calculus considerably for anyone who has moved to the new regime.
About This Guide
This guide is based on current interest rates and rules for EPF, PPF, and NPS as of FY 2025-26 and FY 2026-27, sourced from EPFO, the Ministry of Finance’s quarterly small savings notifications, and PFRDA guidelines. FinanceChecks.com is not a registered investment advisor, and this article does not constitute personalised financial advice. NPS returns are market-linked and not guaranteed; EPF and PPF rates are declared periodically and subject to change. Please consult a qualified financial advisor for guidance specific to your retirement goals and tax situation.
What Each One Actually Is
EPF (Employees’ Provident Fund) is not something you choose; it’s a mandatory retirement savings mechanism for salaried employees at companies above a certain size. Every month, 12 percent of your basic salary is deducted, and your employer contributes a matching 12 percent, though a portion of the employer’s share, 8.33 percent, actually flows into the Employees’ Pension Scheme rather than your EPF balance directly, with the remaining 3.67 percent going into EPF. The current interest rate is 8.25 percent, declared annually by the Central Board of Trustees at EPFO, and since this interest is tax-free up to a threshold, EPF delivers one of the highest genuinely risk-free, tax-adjusted returns available in India. The single most important rule with EPF is never to withdraw it when switching jobs; transferring your balance via your Universal Account Number preserves continuity and lets compounding keep working uninterrupted.
PPF (Public Provident Fund) is a voluntary, long-term government savings scheme open to any Indian citizen, salaried or self-employed, not tied to your job in any way. You can contribute anywhere from ₹500 to ₹1.5 lakh per year, and the current rate is 7.1 percent per annum for the Jan-Mar 2026 quarter, a rate that’s remained fairly stable across recent quarters, reviewed and notified by the Ministry of Finance every quarter. PPF carries what’s called EEE status, exempt-exempt-exempt, meaning your contribution, the interest earned, and the maturity amount are all completely tax-free, making it one of the cleanest tax-efficient instruments available regardless of which tax regime you’re in for the exemption itself, though the 80C deduction on your contribution only applies under the old regime. PPF has a 15-year lock-in, though it can be extended indefinitely in blocks of five years after maturity, and a widely cited strategy is to keep the account running well past 15 years without adding fresh money, since the interest earned on an already-large corpus in the later years is where PPF’s compounding becomes genuinely powerful.
NPS (National Pension System) is fundamentally different in structure from both EPF and PPF. It’s a market-linked retirement account regulated by PFRDA, where your contributions are invested across equity, corporate bonds, and government securities in proportions you can largely choose yourself, with equity exposure allowed up to 75 percent depending on your chosen scheme and age. Because a portion of your money genuinely sits in the stock market, NPS carries real market risk and no guaranteed return, but it also has meaningfully higher long-term return potential than either EPF or PPF, particularly over a 15 to 25-year horizon. The trade-off comes at retirement: only up to 60 percent of your NPS corpus can be withdrawn as a lump sum, tax-free, while the remaining 40 percent must be used to purchase an annuity, which then pays you a monthly pension, itself taxable as income.
The Returns Comparison, Honestly
Over the last several years, EPF has consistently offered the highest guaranteed rate among the three, at 8.25 percent for FY 2025-26, compared to PPF’s steadier but lower 7.1 percent. NPS doesn’t offer a “declared” rate at all, since its return depends entirely on how your chosen equity and debt allocation performs, but over long, multi-decade horizons, NPS’s equity component has historically had the potential to outperform both EPF and PPF, precisely because equity markets have historically delivered higher long-term returns than fixed-income instruments, at the cost of short-term volatility that neither EPF nor PPF exposes you to.
It’s worth being clear-eyed about what this actually means for your decision. If your priority is capital safety and predictable growth, EPF and PPF are structurally built for exactly that. If your priority is maximising long-term corpus size and you have the time horizon and risk tolerance to ride out market volatility along the way, NPS’s equity exposure is specifically designed to capture upside that neither of the other two can offer.
The Tax Picture Has Genuinely Changed
This is the part of the comparison that has shifted the most recently, and it’s worth understanding clearly before assuming any of the classic “tax-saving” logic around these three instruments still applies to you. With the new tax regime now the default for most taxpayers, the traditional 80C deduction of up to ₹1.5 lakh, which covers EPF and PPF contributions, and the additional ₹50,000 NPS deduction under Section 80CCD(1B), are both restricted to the old tax regime only. If you haven’t specifically opted out into the old regime, these deductions simply don’t apply to you anymore.
There is one meaningful exception worth knowing well: employer contributions to your NPS account under Section 80CCD(2) remain deductible even under the new tax regime. This is a genuinely distinct benefit, since it doesn’t require you to opt into the old regime at all, and it effectively means that if your employer offers an NPS contribution as part of your salary structure, that specific portion continues to reduce your taxable income regardless of which regime you file under. It’s worth checking with your HR team whether your employer offers this as a structured benefit, since it’s one of the few genuinely “free,” regime-independent tax advantages left in this entire comparison.
Withdrawal Rules and Liquidity, Compared
EPF allows full withdrawal after two months of continuous unemployment, or at retirement age, and partial withdrawals are permitted after five to seven years of service for specific purposes like a home purchase, up to 90 percent of the balance, medical emergencies, education, or marriage, each with its own eligibility threshold. PPF has a firm 15-year lock-in, though partial withdrawals are allowed from the seventh year onward, and loans against the balance are available even earlier, between the third and sixth year. NPS is the most restrictive of the three by design, since it’s specifically built for retirement rather than as a general-purpose long-term savings account: full withdrawal is only available at age 60, and even then 40 percent must go into an annuity rather than being taken as cash, with limited partial withdrawal allowed for specific life events like a child’s education, a home purchase, or a medical emergency, capped at 25 percent of your own contributions.
So Which One Should Actually Carry Your Retirement Plan
The honest, slightly unsatisfying answer is that for most salaried Indians, this isn’t really a “pick one” decision at all; the strongest retirement strategy typically layers all three together, each serving a distinct role rather than competing for the same rupee.
Think of EPF as your mandatory, guaranteed base. It’s automatic, disciplined by design since the money leaves your salary before you can spend it, and boosted by your employer’s matching contribution, which is effectively free money you’d be leaving on the table by not letting it accumulate fully. For most salaried employees, this alone forms a meaningful, low-effort retirement foundation.
Think of PPF as your additional, predictable stability layer, particularly valuable if you’re self-employed and don’t have access to EPF at all, or if you want a genuinely tax-free, government-guaranteed bucket beyond your EPF balance. It won’t deliver the highest returns of the three, but its stability and complete tax exemption make it a reasonable complement to a portfolio that also includes market-linked exposure elsewhere.
Think of NPS as your dedicated retirement-investing bucket, the one place in your financial plan specifically designed to combine long-term equity growth with retirement-specific structure and discipline, including the annuity mandate that, however restrictive it feels now, does guarantee you a stream of pension income later in life, a feature none of your other investments naturally provide.
A rough, commonly cited allocation for a salaried employee with a comfortable income is to let EPF run as the automatic base, add PPF for extra stability up to whatever comfortable annual amount fits your budget, and use NPS specifically to capture the employer’s 80CCD(2) contribution if offered, along with any additional voluntary contribution you’re comfortable locking away until 60 in exchange for equity-linked growth potential.
My Take
What I think trips people up most in this comparison isn’t a lack of information, all three schemes are well-documented and easy enough to research individually, it’s the framing of the question itself. “Which one is best” assumes these three are competing for the same job, when in reality they’re built to do genuinely different things: guaranteed stability, tax-free predictability, and long-term growth potential, respectively. Rohit’s situation, contributing to all three without quite knowing why, isn’t actually a mistake in itself; the real gap is not having a clear sense of what role each one is meant to play in his eventual retirement income. My honest suggestion is to stop asking which one to pick, and instead ask what proportion of your retirement corpus you want to come from guaranteed, inflation-beating stability versus market-linked growth, and let that answer, rather than any single scheme’s headline interest rate, guide how you split your contributions across all three.
Frequently Asked Questions
1. What is the current EPF interest rate? The EPF interest rate is 8.25 percent for FY 2025-26, declared by the Central Board of Trustees at EPFO. This rate is reviewed and announced annually and can change from year to year.
2. What is the current PPF interest rate? The PPF interest rate is 7.1 percent per annum for the Jan-Mar 2026 quarter, reviewed and notified by the Ministry of Finance every quarter. This rate has remained relatively stable across several recent quarters.
3. Is NPS riskier than EPF and PPF? Yes, genuinely. NPS is market-linked, meaning a portion of your money is invested in equity and bonds, with returns depending on market performance rather than a guaranteed declared rate, unlike EPF and PPF, which are both fixed-income, government-backed instruments.
4. Can I claim tax deductions for EPF, PPF, and NPS under the new tax regime? Generally, no. The Section 80C deduction (covering EPF and PPF) and Section 80CCD(1B) deduction (covering additional NPS contributions) are available only under the old tax regime. The one exception is employer contributions to NPS under Section 80CCD(2), which remain deductible even under the new tax regime.
5. What happens to my EPF if I switch jobs? You should transfer your EPF balance to your new employer using your Universal Account Number (UAN) rather than withdrawing it. Transferring preserves continuity and keeps your accumulated corpus compounding without interruption; withdrawing resets this benefit.
6. Can self-employed individuals use EPF? No. EPF is tied to formal salaried employment at eligible companies. Self-employed individuals can use PPF and NPS instead, both of which are open to any Indian citizen regardless of employment status.
7. What happens to my NPS money at retirement? At retirement (age 60), you can withdraw up to 60 percent of your NPS corpus as a tax-free lump sum. The remaining 40 percent must be used to purchase an annuity, which then pays you a monthly pension, which is taxable as income.
8. Which of the three offers the best liquidity if I need money early? EPF generally offers the most flexible early access, with partial withdrawals allowed after five to seven years for specific purposes. PPF allows partial withdrawal from the seventh year, with loans available even earlier. NPS is the most restrictive, with limited partial withdrawal only for specific life events, capped at 25 percent of your own contributions.
9. Should I contribute to all three, or just pick one? For most salaried Indians, using all three together, EPF as the mandatory base, PPF as an additional stability layer, and NPS as a dedicated long-term growth bucket, tends to build a stronger, more balanced retirement corpus than relying on just one.
10. Is EPF interest completely tax-free? EPF interest is tax-free up to a certain contribution threshold. Interest earned on employee contributions above ₹2.5 lakh per year (or ₹5 lakh per year if the employer doesn’t contribute) becomes taxable at your applicable slab rate, a rule that primarily affects higher-income employees making large voluntary contributions.
Disclaimer
This article is intended for general informational and educational purposes only and does not constitute personalised financial or investment advice. FinanceChecks.com is not a registered investment advisor. Interest rates for EPF and PPF are declared periodically by the relevant authorities and are subject to change; NPS returns are market-linked and not guaranteed. Figures in this article reflect publicly available rates and rules as of September 2026. Please consult a qualified financial advisor and refer to official EPFO, PPF, and PFRDA sources before making retirement planning decisions.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.