
Eternal Shares Rally 36% in Six Months: Is Zomato’s Parent a Buy With 22% Upside Ahead?

Eternal Shares in Focus: Can the Rally Continue?
Eternal Limited, the parent company of Zomato and quick-commerce platform Blinkit, is back on investors’ radar after its shares gained nearly 36% over the past six months.
The rally reflects growing optimism around India’s food delivery and quick-commerce markets, where rising order frequency, a broader customer base and improving operational efficiency could support future growth.
Brokerage firm Joindre Capital Services has assigned a Buy rating to Eternal with a price target of ₹390 per share, indicating potential upside of approximately 22% from the reference price used in its October 2026 research report. The stock closed at ₹323.35 on the BSE on October 9, 2026. At that closing price, the implied upside to ₹390 is approximately 20.6%.
But does the recent rally leave enough room for further gains? And what should investors examine before considering the stock?
Here is a closer look at Eternal’s growth outlook, analyst expectations and the risks that could affect its share price.
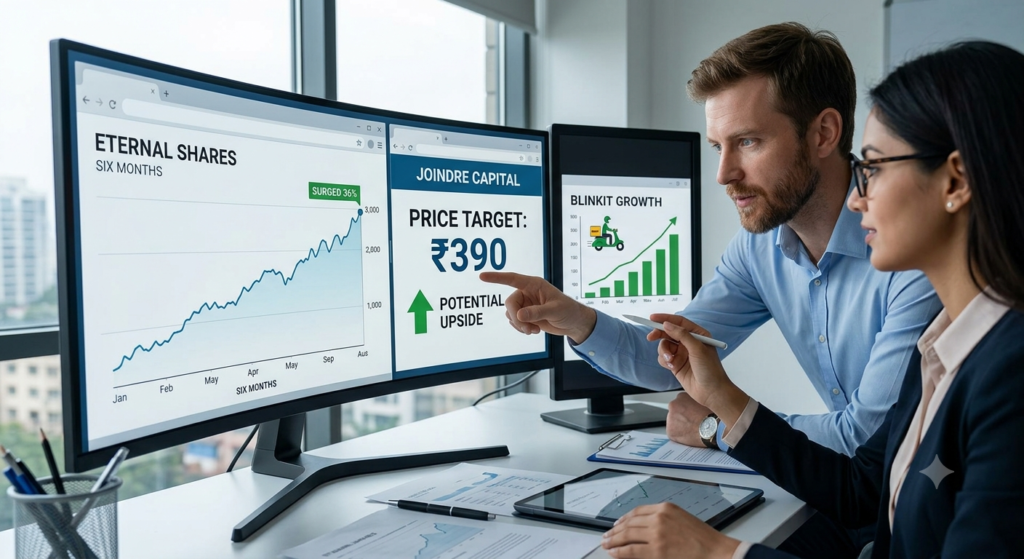
Eternal Shares Price: Key Numbers to Know
| Particulars | Details |
|---|---|
| Company | Eternal Limited |
| Former name | Zomato Limited |
| NSE ticker | ETERNAL |
| Reference share price | ₹323.35 (October 9, 2026, BSE close) |
| Six-month return | Nearly 36% |
| Brokerage | Joindre Capital Services |
| Recommendation | Buy |
| Price target | ₹390 |
| Potential upside | Approximately 20.6% from the reference close |
Source: Market reports and brokerage research available as of October 11, 2026. The upside percentage varies with the share price used as the reference point.
The numbers suggest that analysts see further room for appreciation. However, a brokerage target is an estimate based on assumptions about future business performance and valuation, not a guaranteed return.
Why Are Eternal Shares Rising?
Three major factors are supporting investor interest in Eternal.
1. Blinkit’s Quick-Commerce Growth
Blinkit has become one of Eternal’s most important growth drivers. Its business model focuses on delivering groceries, household essentials and other products within a short period, supported by a network of local fulfilment stores.
The opportunity extends beyond large metropolitan markets. As customers increasingly use quick commerce for frequent, smaller purchases, platforms can potentially improve order density and store productivity.
Eternal’s June 2026 quarter performance highlighted this momentum. According to Reuters, Blinkit’s net order value increased 86% year-on-year, while its network expanded to 2,443 stores.
The company also reported improved adjusted EBITDA at Blinkit, signalling progress towards better operating economics even as it continued investing in expansion.
For investors, the important question is whether Blinkit can sustain this growth while gradually improving profitability. Rapid expansion alone is not enough if the costs of winning and serving customers rise faster than revenue.
2. Food Delivery Growth and Customer Retention
Zomato’s food delivery business remains another important part of Eternal’s investment case.
The business can benefit from repeat orders, wider restaurant selection, improved delivery efficiency and initiatives aimed at making food delivery more affordable.
Joindre Capital’s October 2026 assessment highlighted improving customer retention and affordability-led growth as positive factors.
Better retention matters because repeat customers may generate more orders over time without requiring the company to spend as much on acquiring new customers. If this translates into healthier contribution margins, it could support sustainable earnings growth.
However, investors should monitor whether affordability initiatives attract genuinely incremental orders or simply reduce revenue and margins on purchases customers would have made anyway.
3. Improving Operational Efficiency
For a business operating at scale, efficiency can be just as important as revenue growth.
Eternal needs to manage delivery costs, employee and partner expenses, store operating costs, technology investments and customer incentives while expanding its businesses.
Joindre Capital cited better operating efficiency and improving Blinkit economics as part of its positive outlook.
If order volumes increase faster than fixed operating costs, the company may benefit from operating leverage. This means a greater proportion of incremental revenue can eventually contribute towards profits.
The challenge is to achieve that improvement without sacrificing delivery quality, customer experience or market share.
You May Also Like To Read About:
- Amazon Layoffs: At Least 100 Employees in India Hit by Latest Global Job Cuts: What We Know and What Affected Employees Should Do
- VinFast to Set Up 50+ Electric Two-Wheeler Showrooms in India: 15 States, 34 Cities and EV Market Plans
- Why Mukesh Bansal and Ex-Flipkart Leaders Want an ESOP Buyback
- Ola Electric Rights Issue 2026: ₹1,000 Cr Offer Opens October 22 at ₹27 Per Share
- Nykaa Shares Jump 6% On Strong Q2 FY27 Business Update
- Bhavish Aggarwal Pledges 4.32% Ola Electric Stake To Fund Rights Issue Subscription
Eternal Share Price Target: What Does Joindre Capital Expect?
Joindre Capital Services has assigned Eternal a Buy rating and a target price of ₹390 per share, based on a sum-of-the-parts valuation.
This approach values the company’s business segments separately before combining them to estimate the overall equity value.
It is particularly relevant for Eternal because the company operates across several businesses, including food delivery, quick commerce and its going-out platform, District.
At a reference price of ₹323.35, a move to ₹390 would represent a gain of approximately 20.6%.
For investors, the target depends on several assumptions:
- Blinkit continues expanding while improving store-level productivity and profitability.
- Zomato’s food delivery business maintains healthy growth and customer retention.
- District develops into a more meaningful contributor to the company’s long-term growth.
- Operating costs and competitive pressures remain manageable.
- The market continues assigning attractive valuations to high-growth consumer internet businesses.
If these assumptions hold, Eternal could have further upside. If growth slows or profitability disappoints, the share price may fall short of the brokerage target.
What Are the Biggest Risks for Eternal Investors?
Despite its growth prospects, Eternal is not a risk-free investment.
1. Intense Competition in Quick Commerce
Quick commerce remains a fiercely competitive market. Blinkit must compete on assortment, delivery speed, customer experience, geographic coverage and pricing.
Aggressive discounting by competitors could make it more expensive to acquire customers or defend market share. If Eternal responds with higher incentives, profitability may suffer.
2. High Expansion Costs
Opening new stores and investing in warehouses, technology and supply chains requires substantial capital.
Expansion can strengthen the business over time, but it can also weigh on near-term cash flows and returns on capital. Investors should examine whether new stores achieve acceptable productivity and profitability as they mature.
3. Valuation Risk
A company can deliver strong business growth and still produce disappointing stock returns if its shares are already priced for ambitious future performance.
Investors should therefore compare Eternal’s valuation with its earnings outlook, cash generation, margins and the valuations of comparable businesses.
A Buy rating does not eliminate the possibility of a valuation correction.
4. Profitability May Not Improve as Expected
Higher order volumes do not automatically translate into higher profits. Delivery costs, customer discounts, employee expenses and infrastructure investments can offset revenue growth.
If operating margins fail to improve, the market may revise its expectations for future earnings and reduce the valuation assigned to the stock.
Should You Buy Eternal Shares Now?
Eternal could interest investors seeking exposure to India’s growing online food delivery and quick-commerce markets. Its established food delivery business, Blinkit’s expansion and the potential for improving operating efficiency provide reasons to watch the stock.
However, the decision depends on an investor’s purchase price, investment horizon, risk tolerance and assessment of valuation.
Investors considering Eternal should evaluate:
- The latest quarterly revenue and profit growth.
- Blinkit’s order-value growth, store productivity and profitability.
- Food delivery growth and contribution margins.
- Cash flows and spending on expansion.
- Current valuation relative to expected earnings growth.
- The possibility of downside if the market’s growth expectations are not met.
Those with a long-term horizon should focus on sustainable earnings and cash generation rather than relying solely on recent share-price performance. Short-term traders, meanwhile, should recognise that a stock can correct even when its underlying business remains strong.
The Bottom Line
Eternal’s nearly 36% six-month rally reflects optimism about the company’s position in food delivery and quick commerce. Joindre Capital Services’ ₹390 target suggests that further gains may be possible, provided growth and profitability continue to develop as expected.
Blinkit’s expansion, customer retention and operating efficiency are key indicators to watch. Competition, expansion costs and valuation remain significant risks.
For investors, the central question is not simply whether Eternal can reach ₹390. It is whether the company’s future earnings and cash flows can justify the price paid today.
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Brokerage ratings and price targets are estimates, not guarantees. Share prices can rise or fall, and investors should conduct independent research or consult a SEBI-registered investment adviser before making investment decisions.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.

[…] Eternal Shares Rally 36% in Six Months: Is Zomato’s Parent a Buy With 22% Upside Ahead? […]
[…] Eternal Shares Rally 36% in Six Months: Is Zomato’s Parent a Buy With 22% Upside Ahead? […]