Primary Owner vs Co-Owner vs Co-Borrower on a Home Loan: What Each Term Actually Means Legally

By the FinanceChecks.com Editorial Team | Published September 30, 2026 | Last reviewed September 30, 2026 | 9-minute read
Four words get thrown around almost interchangeably when a family buys a house together: owner, co-owner, borrower, co-borrower. Banks use some of them, property registration documents use others, and the Income Tax Act cares about a very specific combination of them. Most people sign a stack of home loan paperwork assuming these terms all mean roughly the same thing, and then discover years later, often at tax filing time or during a property dispute, that they do not.
This guide breaks down exactly what each term means legally, how they relate to each other, and why the specific combination you have determines both your legal rights to the property and your tax benefits on the loan.
Quick Answer
A primary owner or co-owner is defined by what the property registration documents and sale deed say, and this is what determines actual legal ownership of the house. A co-borrower or co-applicant is defined by what the loan agreement with the bank says, and this determines legal liability for repaying the loan. These two things are legally independent of each other: you can be a co-borrower on the loan without owning any share of the property, and in theory you could be a co-owner of the property without being a party to the loan at all, though banks rarely allow this. The tax benefits under Section 80C and Section 24(b) of the Income Tax Act are available only to someone who is both a co-owner of the property and a co-borrower who is actually contributing to loan repayment. Being only a co-borrower, with no ownership share on the registration documents, generally disqualifies you from claiming these deductions, no matter how much of the EMI you are paying.
About This Guide
This guide was compiled by the FinanceChecks.com editorial team using the Income Tax Act’s provisions under Sections 24(b), 80C, 80EE and 80EEA, the Transfer of Property Act, 1882, and published guidance from banks and tax advisory sources on joint home loan structuring. Because the terminology here is widely used inconsistently, including by banks themselves in informal communication, we have focused on the legal substance behind each term rather than just the label used in any particular document. We recommend confirming your specific loan and ownership structure with your bank’s sanction letter and your property’s registration documents, since these two documents together define your actual legal position.
The Core Distinction: Ownership Documents vs Loan Documents
Before looking at each term individually, it helps to understand the one principle that explains almost all the confusion: ownership and loan liability are governed by two completely different sets of documents, and a bank or a loan agreement cannot, by itself, make you a legal owner of a property.
Your rights to the property, including whether you are the sole owner, a co-owner, or have no ownership interest at all, are determined by the property’s registered sale deed and related title documents filed with the local sub-registrar. Your liability for repaying the loan is determined by the loan agreement you sign with the bank, which is a completely separate legal document. A person’s name can appear on one of these documents and not the other, and this mismatch is exactly where most of the confusion, and in some cases genuine financial risk, arises.
Primary Owner
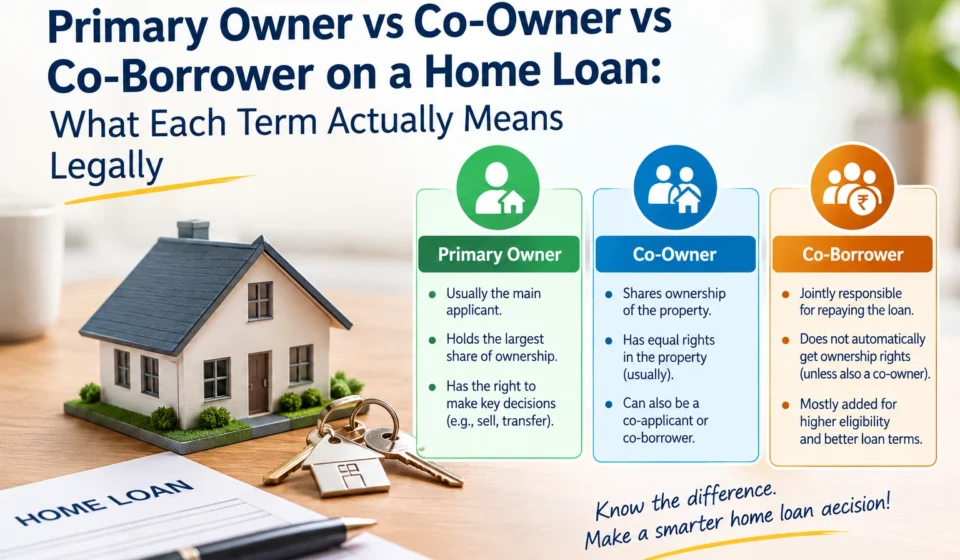
The primary owner is simply the first-named, or principal, owner on the property’s title documents. In a solely owned property, there is only one owner and the term barely matters. In a jointly owned property, the primary owner is typically the person listed first on the sale deed, and this designation can sometimes affect administrative matters like which name appears first on property tax records or utility connections, though it does not automatically mean that person owns a larger share of the property than the other owners, unless the ownership proportions are specifically stated in the deed itself.
Co-Owner
A co-owner is a person who holds a genuine, legal share in the property itself, as recorded on the registered sale deed or title documents. This is the single most important status to understand, because it is co-ownership, not loan involvement, that gives a person actual legal rights over the property, including the right to use it, the right to a share of its value if sold, and the right to pass on that share through inheritance.
Under Indian law, a co-owner generally cannot be a minor or anyone otherwise ineligible to enter into legal contracts. When a home loan is involved, banks typically require every co-owner of the property to also be a party to the loan, usually as a co-borrower, since lenders are generally unwilling to finance a property where some legal owners have no corresponding repayment obligation. A co-owner shares liability for the loan to the same extent as the primary borrower when they are also a co-borrower, which is the arrangement banks usually insist on.
Co-Borrower (Also Called Co-Applicant)
A co-borrower, sometimes also referred to as a co-applicant, is a person who jointly applies for and signs the home loan agreement alongside the primary borrower, taking on equal legal responsibility for repaying the loan. This is purely a loan relationship with the bank and says nothing, by itself, about whether that person owns any share of the property.
Banks generally allow close relatives, most commonly a spouse, parent, or adult child, to be added as a co-borrower, and doing so has a genuinely useful practical benefit: because loan eligibility is assessed on combined income, adding a co-borrower with a steady income can meaningfully increase the total loan amount a bank is willing to sanction. This is often the real reason families add a second person to a loan, well before anyone has thought carefully about what it means for property ownership and tax claims.
Critically, a co-borrower who is not also a co-owner of the property has full legal liability to repay the loan but no legal ownership claim over the house itself. This exact combination, liability without ownership, is the situation at the heart of many family disputes that surface years after a loan is taken.
Co-Signer or Guarantor
A co-signer, sometimes called a guarantor, is a distinct and more limited role. This person guarantees that the loan will be repaid, but their liability is triggered only if the primary borrower and any co-borrowers default on the loan. A guarantor does not have any ownership claim to the property and does not receive any tax benefits related to the loan, since their involvement is a backstop for the bank’s risk, not a financial contribution to the purchase itself.
Comparing the Roles at a Glance
| Role | Defined By | Legal Ownership of Property? | Liable for Loan Repayment? | Eligible for Tax Benefits? |
|---|---|---|---|---|
| Primary Owner | Property title/sale deed | Yes | Only if also a borrower on the loan | Yes, if also a co-borrower contributing to EMI |
| Co-Owner | Property title/sale deed | Yes | Only if also a borrower on the loan | Yes, if also a co-borrower contributing to EMI |
| Co-Borrower / Co-Applicant | Loan agreement with the bank | No, unless separately named on the title | Yes, equally with the primary borrower | Only if also a registered co-owner |
| Co-Signer / Guarantor | Loan agreement with the bank | No | Only if the borrower(s) default | No |
The table makes the core trap visible at a glance: a co-borrower’s tax eligibility depends entirely on whether they also appear on the title, not on how much of the EMI they personally pay.
You May Also Like To Read About:
- Why Some Financial Advisors Say Never Pay Off Your Home Loan Early, and Whether That’s Actually Good Advice
- Claiming Both HRA Exemption and Home Loan Interest Deduction: Know When It’s Allowed — and When It’s Not
- The Home Loan Nobody Explains to You Before You Sign It
- What Happens to Your Joint Bank Account, Home Loan, and Shared Debts After a Divorce in India?
- What Happens to Loan EMIs and Autopay Mandates If You Die Before Anyone Tells the Bank
Why the Combination Matters More Than Any Single Label
The most consequential point in this entire topic is this: being a co-borrower alone, without being a registered co-owner, does not entitle you to claim home loan tax deductions, no matter how much of the EMI you are actually paying out of your own income. The Income Tax Act’s deductions under Section 24(b), for interest paid on a home loan, and Section 80C, for principal repayment, are available only to someone who is both a legal co-owner of the property and a co-borrower actually contributing to the loan’s repayment.
This creates a very specific and common real-world scenario worth naming directly: if a property is registered with your spouse as the sole or primary owner, and you are added only as a co-borrower on the loan to strengthen loan eligibility, but you are not listed as a co-owner on the sale deed, you generally cannot claim your share of the Section 24(b) or Section 80C deductions, even though you may be paying most or all of the EMI yourself. Your spouse, as the sole registered owner, would typically be the one entitled to claim the full available deduction, regardless of whose bank account the EMI is actually debited from.
The Tax Numbers When Both Conditions Are Met
When both spouses are correctly structured as co-owners and co-borrowers, each contributing to EMI repayment, the household’s combined tax benefit roughly doubles compared to a single-name purchase. Under the old tax regime, each co-owner-cum-co-borrower can individually claim up to ₹2 lakh per year under Section 24(b) for interest on a self-occupied property, and up to ₹1.5 lakh per year under Section 80C for principal repayment, giving a combined household benefit of up to ₹7 lakh per year across both spouses, compared to roughly ₹3.5 lakh available to a single owner-borrower. Additional deductions may also be available under Sections 80EE or 80EEA for eligible first-time buyers, subject to their specific conditions. Each co-owner can generally only claim a deduction proportionate to their share of ownership and their actual contribution to repayment, not an arbitrary or equal split simply because both names appear on the documents.
What to Check Before You Sign Anything
If you are about to take a joint home loan, a few checks before signing can prevent the exact mismatch described above. Confirm explicitly whether you are being added to the property’s sale deed as a co-owner, not just to the bank’s loan application as a co-borrower, since these are two separate forms with two separate purposes. Ask the bank or your lawyer to clarify, in writing, what percentage ownership share you hold if you are added as a co-owner, since this share can determine how much of the tax deduction you are entitled to claim. If your actual intention is to pay a significant share of the EMI, insist on co-ownership rather than accepting a co-borrower-only arrangement, specifically to preserve your tax claim and your legal stake in the property. Keep your own bank records of EMI payments regardless of your ownership status, since you will need proof of your actual financial contribution if you are a co-owner claiming a deduction proportionate to your contribution, or if a dispute over contribution ever arises later.
Common Mistakes Families Make
A frequent mistake is assuming that being named as a co-borrower on the home loan automatically means co-ownership of the property, when these are governed by entirely separate documents and one does not create the other. Another common mistake is paying the EMI from one spouse’s account for convenience without checking whether that spouse is actually a registered co-owner, which can mean years of EMI payments generate no tax benefit at all for the person actually paying. Families also frequently assume tax benefits are split automatically and equally between co-owners, when in reality each co-owner can generally only claim a deduction proportionate to both their ownership share and what they have actually contributed toward repayment. Finally, many families add a co-borrower purely to increase loan eligibility without having the parallel conversation about property ownership shares, which can leave the arrangement unresolved for years until a death, divorce, or sale forces the question.
My Take
The gap between these terms exists precisely because two different institutions, the bank and the property registrar, are tracking two entirely different things, and nobody in the transaction is naturally positioned to point out that the two records need to match for the arrangement to actually work the way a family assumes it does. Banks are focused on loan recovery and income eligibility, which is why they are often relatively relaxed about adding a co-borrower; they are not in the business of advising you on property law or tax optimisation.
If you take one thing from this guide, it should be a simple question to ask before signing a joint home loan: am I being added as a co-owner on the property, a co-borrower on the loan, or both? The answer determines your legal stake in the house, your tax benefits, and, as a later guide in this series covers, what happens to your contribution if the relationship changes or a co-owner passes away. It is a five-minute conversation with your bank or lawyer now, against what can otherwise become a genuinely difficult conversation years later.
Frequently Asked Questions
1. What is the difference between a co-owner and a co-borrower on a home loan? A co-owner has a legal share in the property itself, as recorded on the registered sale deed. A co-borrower has signed the loan agreement and is liable for repayment, but this does not by itself give them any ownership share in the property.
2. Can I be a co-borrower without being a co-owner of the property? Yes. This is a common arrangement, often done to increase loan eligibility, but it means you are liable for repaying the loan without having a legal ownership claim to the property.
3. Do I get tax benefits if I’m paying the EMI but I’m not listed as a property owner? Generally, no. Tax deductions under Section 24(b) and Section 80C require you to be both a co-owner of the property and a co-borrower contributing to repayment. Paying the EMI alone, without being a registered co-owner, typically does not entitle you to claim these deductions.
4. What is the difference between a co-applicant and a co-borrower? These terms are generally used interchangeably in the home loan context. Both refer to a person who applies for and shares liability on the loan alongside the primary borrower.
5. What is a co-signer or guarantor, and how is it different from a co-borrower? A co-signer or guarantor is only liable to repay the loan if the primary borrower and co-borrowers default. They have no ownership claim to the property and no tax benefits, unlike a co-borrower who is equally liable from the start.
6. If both spouses are co-owners and co-borrowers, how much tax benefit can the household claim? Each spouse can individually claim up to ₹2 lakh per year under Section 24(b) for interest and up to ₹1.5 lakh under Section 80C for principal, giving a combined household benefit of up to ₹7 lakh per year under the old tax regime, subject to actual ownership share and contribution.
7. Can a homemaker spouse with no income be added as a co-owner? Yes, a co-owner does not need to have independent income, but they generally also need to be a co-borrower on the loan if the bank requires it, and without income or EMI contribution, they would not be able to claim a tax deduction of their own.
8. Does the order of names on the sale deed matter? The first-named or “primary” owner designation can affect some administrative records, but it does not automatically determine ownership proportion unless the deed specifically states each owner’s share.
9. Can I be added as a co-owner of the property without being on the loan at all? In principle, yes, but most banks require every registered co-owner of the property to also be a party to the loan, since lenders are generally unwilling to finance a property where a legal owner has no repayment obligation.
10. What should I check before agreeing to be added to a home loan? Confirm explicitly whether you are being added as a co-owner on the sale deed, a co-borrower on the loan, or both, and get your ownership percentage in writing if you are a co-owner, since this affects both your legal rights and your tax claims.
Disclaimer
This article is for general informational purposes only and does not constitute legal or tax advice. Tax deduction limits, eligibility conditions and ownership rules can change with amendments to the Income Tax Act, and your specific entitlement depends on your individual loan agreement, property title documents and ownership share. Readers should consult a property lawyer and a qualified tax professional before structuring a joint home loan or property purchase. FinanceChecks.com is not a law firm or a tax advisory service.
Last reviewed and fact-checked on September 30, 2026 by the FinanceChecks.com Editorial Team.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.