Bonus Shares vs Stock Split: What’s the Real Difference for Investors?

Priya’s father called her, uncharacteristically pleased with himself, to share the news. “The company gave me free shares,” he said. “One extra share for every one I already had. Just like that.”
Priya, who had recently gone through her own confusion over a completely different corporate action in her own portfolio, a stock split, immediately asked the question that actually matters: “Did the price also drop by half?”
It had. Her father’s excitement dimmed slightly once she walked him through it, his total holding value hadn’t budged, he just had double the shares at half the price. “So this is the same as your split thing?” he asked.
It isn’t, and the distinction genuinely matters, not just for understanding what happened to your portfolio, but for how it’s taxed, what it signals about the company issuing it, and what regulatory hoops the company actually had to clear to do it. A stock split and a bonus issue look nearly identical from the outside, more shares, lower price, same total value, but they are built on completely different mechanics underneath. Here’s exactly how they differ.
Quick Answer
A bonus issue and a stock split both increase the number of shares you hold while proportionally reducing the price, leaving your total investment value unchanged either way. The real difference lies underneath: a bonus issue creates new shares by capitalising the company’s free reserves into paid-up share capital, an actual accounting transfer that requires the company to have adequate reserves and meet SEBI eligibility conditions. A stock split simply subdivides the existing face value of shares with no reserves involved at all. This distinction also carries into taxation: bonus shares get a fresh cost of acquisition of zero and a new holding period from the date of allotment, while split shares retain your original cost and holding period.
About This Guide
This guide has been researched and written by the FinanceChecks editorial team, based on SEBI’s Issue of Capital and Disclosure Requirements (ICDR) Regulations governing bonus issues, the Companies Act, 2013, and the Income Tax Act’s provisions on the cost of acquisition and holding period for bonus shares.
FinanceChecks is an independent Indian personal finance publication. We are not SEBI-registered investment advisers, and nothing in this article is a recommendation to buy or sell any specific stock. Please read the disclaimer at the end of this guide.
Last reviewed: September 2026
The Surface Similarity That Causes All the Confusion
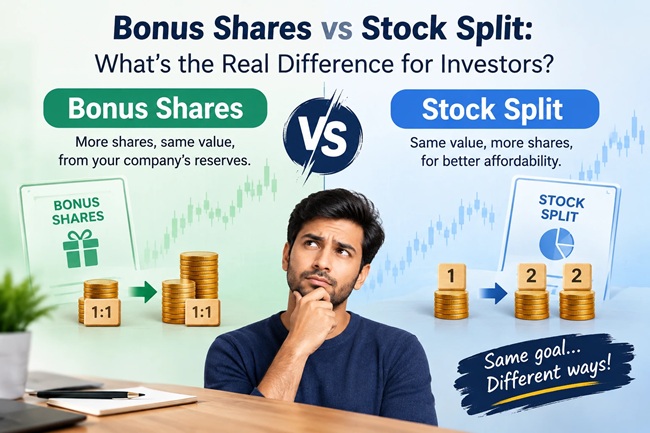
Both corporate actions produce the same visible outcome in your demat account: more shares show up, the per-share price drops proportionally, and your total holding value stays exactly where it was.
| What you observe | Bonus issue | Stock split |
|---|---|---|
| Number of shares | Increases | Increases |
| Price per share | Decreases proportionally | Decreases proportionally |
| Total holding value | Unchanged | Unchanged |
| Your ownership percentage in the company | Unchanged | Unchanged |
If you only look at what shows up on your screen, they are indistinguishable. The difference lives entirely in the mechanism behind the scenes, and that mechanism is where the practical consequences actually diverge.
You May Also Like To Read About:
What’s Actually Happening Underneath: Reserves vs Face Value
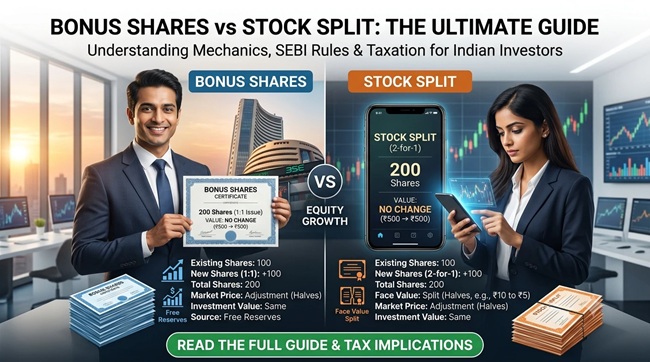
A bonus issue is a capital restructuring. The company takes money sitting in its free reserves, retained earnings, general reserve, or securities premium account, and converts it into paid-up share capital by issuing new shares to existing shareholders at no cost, in a fixed ratio such as 1:1 or 2:1. This is a genuine accounting transfer from one part of the balance sheet, reserves, to another, paid-up capital. The company’s net worth doesn’t change, but the composition of that net worth does.
A stock split touches none of this. It simply redefines the face value of existing shares, say from ₹10 to ₹2, and issues the corresponding additional shares to reflect that new, lower denomination. No reserves move. No capital account changes composition. It is purely an arithmetic subdivision of what already existed, closer to breaking a ₹100 note into five ₹20 notes than to receiving new money.
This is the structural heart of the difference: a bonus issue moves value between accounting categories inside the company. A stock split doesn’t move anything at all, it just changes the denomination.
Why Companies Choose One Over the Other
Bonus issues are generally read as a reward to existing shareholders and a signal of financial health, since a company needs sufficiently large free reserves to fund one in the first place. It’s a way to convert idle reserves into a more visible form without any cash leaving the company, and it increases the floating stock available in the market without diluting anyone’s percentage ownership.
Stock splits exist almost entirely for affordability and liquidity. A company with a share price that has climbed into a range some retail investors find intimidating, ₹20,000 or ₹30,000 per share, might split simply to bring the sticker price down and widen its potential buyer base, entirely independent of whether it has large reserves to spare.
A useful rule of thumb: if a company is highlighting its strong reserves and rewarding loyal shareholders, that’s bonus-issue territory. If a company is mainly trying to make its stock feel more “buyable” at a lower headline price, that’s stock-split territory.
The Regulatory Bar Is Different Too
Because a bonus issue actually consumes company reserves, SEBI’s ICDR Regulations impose real eligibility conditions before a listed company can announce one, conditions that don’t apply to a stock split at all. Broadly, a company must have sufficient free reserves or securities premium to fully capitalise the bonus, must not have defaulted on payment of interest or principal on fixed deposits or debt securities, must not have defaulted on statutory dues to employees such as provident fund or gratuity, and must complete the bonus allotment within a defined timeline after board approval, generally within two months.
A stock split faces none of these specific capital-adequacy tests, since no reserves are being touched. It largely just requires shareholder and board approval and the standard exchange disclosure process.
The Tax Difference Most People Get Wrong
This is the single most practically important distinction, and it’s the one most casual explanations skip entirely.
| Tax treatment | Bonus shares | Split shares |
|---|---|---|
| Cost of acquisition for capital gains | Treated as nil (zero) | Original cost, apportioned across the new share count |
| Holding period for LTCG/STCG | Starts fresh from the date of allotment of the bonus shares | Carries forward unchanged from the original purchase date |
| Is it a taxable event on receipt | No | No |
Here’s why this matters in practice. Say you bought 100 shares at ₹500 each two years ago, total cost ₹50,000. If the company later gives you a 1:1 bonus, you now hold 200 shares. Your original 100 shares still carry your original ₹50,000 cost and your original two-year-old holding period. But your new 100 bonus shares carry a cost of acquisition of zero and a holding period that starts counting from the day they were allotted, not from when you bought the original shares.
This means if you sell some of those bonus shares within 12 months of allotment, the entire sale proceeds could be taxed as short-term capital gains, even though you’ve technically “held this investment” for two years in your own mind. A stock split creates no such trap, since split shares simply inherit your original purchase date and cost basis in full, with no fresh clock starting anywhere.Bonus Shares vs Stock Split: Quick Comparison Table
| Feature | Bonus Issue | Stock Split |
|---|---|---|
| Mechanism | Capitalises free reserves into paid-up capital | Subdivides existing face value |
| Face value | Unchanged | Reduced proportionally |
| Company reserves | Decrease (converted to capital) | Untouched |
| SEBI capital-adequacy conditions | Yes, strict eligibility criteria apply | No specific reserves-based conditions |
| Cost of acquisition for new shares | Nil (zero) | Same as original, apportioned |
| Holding period for new shares | Fresh, from date of allotment | Same as original purchase date |
| Primary company motivation | Reward shareholders, signal strength, use reserves | Improve affordability and liquidity |
Common Mistakes Investors Make Between the Two
Treating them as interchangeable. They produce a visually similar outcome, but different mechanisms, different regulatory requirements, and critically different tax consequences sit underneath.
Assuming bonus shares carry the same holding period as your original investment. This is the costliest mistake on this list. Selling bonus shares within 12 months of allotment, believing your “real” holding period is much longer because you’ve owned the underlying investment for years, can result in an unexpected short-term capital gains tax bill.
Assuming a bonus issue is always a stronger positive signal than a split. Both can be entirely neutral moves dressed up as good news. A bonus issue does require real reserves, but that alone doesn’t tell you anything about the company’s future growth or whether the stock is a good buy.
Ignoring the record date and mixing up your bonus versus original share lots when calculating tax on a later sale. Since the two lots have different costs and holding periods, keeping them separately tracked matters enormously at sale time, especially if you sell only part of your holding.
My Take
I think the tax distinction is where this comparison actually earns its keep, because everything else, the price drop, the extra shares, the unchanged total value, looks basically the same to an investor scrolling through their portfolio app. The zero-cost, fresh-holding-period treatment of bonus shares is the kind of detail that doesn’t matter at all until the day you decide to sell part of your position, and then it can matter quite a lot, especially if you sell within a year of a bonus allotment without realising the clock reset on exactly those shares.
I’d also gently push back on reading too much into either action as a signal about where the stock is headed. A bonus issue tells you a company has healthy reserves and chose to convert some into paid-up capital. It says nothing definitive about future earnings or valuation. A split tells you even less, mainly that management wanted a lower sticker price. Neither event should move your conviction about the underlying business one way or the other; the fundamentals that mattered the day before either action was announced are exactly the fundamentals that matter the day after.
My honest advice, echoing Priya’s instinct with her father: whenever “free shares” show up, the first question worth asking isn’t whether it’s good news, it’s exactly what happened structurally, because that’s what determines what you owe the tax department later.
Frequently Asked Questions
1. Is a bonus share issue the same as a stock split?
No. Both increase your share count and proportionally lower the price, but a bonus issue converts company reserves into paid-up capital, while a stock split simply subdivides the existing face value with no reserves involved.
2. Do I pay anything to receive bonus shares?
No. Bonus shares are issued free of cost to existing shareholders in a fixed ratio, funded entirely from the company’s own free reserves.
3. What is the cost of acquisition for bonus shares when I eventually sell them?
It is treated as nil, or zero, for capital gains tax purposes, unlike split shares, which retain your original purchase cost apportioned across the new share count.
4. Does the holding period for bonus shares start from when I bought the original shares?
No. The holding period for bonus shares starts fresh from their date of allotment, separate and distinct from the holding period of the original shares that earned you the bonus.
5. Can I sell my bonus shares immediately after receiving them?
Yes, there’s no lock-in preventing you from selling immediately, but doing so within 12 months of allotment means any gain is taxed as short-term capital gains, since the holding period clock started on allotment, not on your original purchase.
6. Why do some companies choose a bonus issue instead of a stock split?
A bonus issue signals that a company has strong free reserves and chooses to reward shareholders by converting some of those reserves into visible, tradeable capital. A stock split, by contrast, doesn’t require any reserves at all and is mainly used to make shares more affordable and liquid.
7. Are there eligibility conditions a company must meet to issue bonus shares?
Yes. Under SEBI’s ICDR Regulations, a company must have adequate free reserves, must not have defaulted on debt or fixed deposit payments, and must not have defaulted on statutory employee dues, among other conditions, before it can issue bonus shares.
8. Does a stock split have similar eligibility conditions?
No, since a stock split doesn’t touch company reserves, it doesn’t face the same capital-adequacy tests that apply to a bonus issue, though it still requires standard board and shareholder approval.
9. Does my ownership percentage in the company change after a bonus issue or split?
No, in both cases your proportional ownership stays exactly the same, since every shareholder receives additional shares in the same ratio.
10. Which is a stronger signal of company health, a bonus issue or a stock split?
Neither should be read as a definitive signal about future performance. A bonus issue does require genuine reserves, which can reflect financial health, but it says nothing conclusive about growth prospects or valuation. A split says even less, mainly reflecting a decision about share price optics.
Key Takeaways
- Both a bonus issue and a stock split increase your share count and lower the price proportionally, with zero change to your total holding value or ownership percentage.
- A bonus issue capitalises company reserves into paid-up capital and requires SEBI eligibility conditions around reserves and no defaults; a stock split simply subdivides face value with none of these requirements.
- Bonus shares get a cost of acquisition of nil and a fresh holding period from the date of allotment, a genuine tax trap if sold within 12 months without realising this.
- Split shares retain your original cost of acquisition and original holding period, with no fresh tax clock starting.
- Neither event should be treated as a standalone signal to buy or sell; the underlying business fundamentals remain the real basis for any investment decision.
Disclaimer
The information provided in this article is for educational and informational purposes only and should not be construed as investment or tax advice, or a recommendation to buy, sell, or hold any specific security.
FinanceChecks.com is not a SEBI-registered investment adviser, tax consultant, or research analyst. Tax provisions referenced in this article reflect the law as understood in September 2026 and are subject to change through legislative amendment.
Please consult a qualified chartered accountant for guidance specific to your own tax situation, particularly around calculating capital gains on bonus or split shares, and consult a SEBI-registered investment adviser before making investment decisions.
FinanceChecks.com and its authors accept no liability for any loss arising from reliance on the information presented in this article.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.