Annual Fee Charged on an Unused Credit Card: Does It Hurt Your CIBIL Score, and How to Close the Card Safely

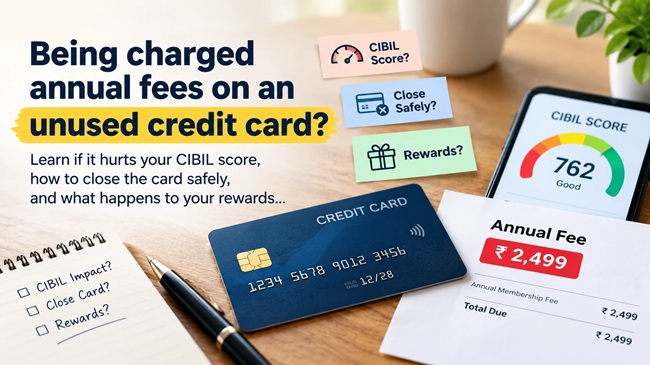
Getting billed an annual fee on a credit card you have not touched in months is one of the more common and avoidable financial irritants for Indian credit card holders. It raises three practical questions at once: whether the unpaid fee can damage your CIBIL score, whether you should simply close the card, and what happens to the reward points sitting unused on it. Each of these has a clear answer once you understand how billing, credit reporting and reward programs actually work in India.
This guide walks through all three questions together, since they are almost always faced at the same time by anyone holding a dormant credit card.
Quick Answer
An unpaid annual fee on a credit card, even one you never use, is treated exactly like any other unpaid credit card bill. If it remains unpaid past the due date, the bank will levy late payment charges and finance charges, and once the account is reported as overdue to credit bureaus, it can lower your CIBIL score. Simply not using the card does not exempt you from the fee or its consequences. If you want to close a long-unused card, you can do so by clearing all dues, calling customer care or submitting a written closure request, and confirming in writing that the account has been closed with a nil balance. Reward points not redeemed before closure are almost always forfeited, since most Indian card issuers treat unused points as void once an account is closed, typically after a short grace window of a few days to about 30 days depending on the issuer.
About This Guide
This guide was compiled by the FinanceChecks.com editorial team by cross-referencing credit bureau practices, RBI’s credit card and debit card master directions, and published card-closure processes from major Indian banks, to give an accurate and actionable answer to a genuinely common problem. We focus on the practical sequence of steps a reader needs, not just the theory of how credit scores work, because a dormant card sitting unresolved for months causes real, compounding financial cost. This article will be updated if RBI or the bureaus change how dormant-account fee disputes are handled.
Does an Annual Fee on an Unused Card Affect Your CIBIL Score?
Yes, it can, and the mechanism is straightforward. Once a bank issues and activates a credit card, an annual fee is typically charged automatically as part of that card’s terms and conditions, regardless of whether you have made a single transaction on it. The fee appears on your monthly statement like any other charge. If you do not pay it by the due date, the bank does not simply write it off. Instead, it usually adds late payment charges and monthly finance charges, which is calculated on the outstanding amount, often in the range of 2 to 3.5% a month, compounding quickly into a balance far larger than the original fee.
If this outstanding amount remains unpaid, the bank reports the account as delinquent to credit bureaus such as CIBIL, Experian, Equifax and CRIF High Mark. This shows up on your credit report as “days past due,” and it is this delinquency status, not the mere existence of an annual fee, that actually damages your credit score. In other words, the annual fee itself is not what hurts you; letting it go unpaid and unresolved is.
There is a separate, smaller effect worth knowing about too. Even if you pay every fee on time, holding a completely dormant card can slightly affect your credit utilisation ratio and the overall mix of active credit in your file, though this impact is generally minor compared to the damage caused by an actual missed payment.
What To Do If You’ve Been Charged an Annual Fee You Don’t Want to Pay
If you do not intend to use the card again, do not simply ignore the fee, since ignoring it is what leads to the finance charges and bureau reporting described above. Instead:
Contact the bank’s customer care as soon as you see the fee on your statement and ask whether the annual fee can be waived, since many banks will waive it, particularly on your first request or if you have been a long-standing customer with no history of missed payments. If a waiver is not possible and you genuinely do not want to keep the card, ask to pay off only the fee that is currently due, then immediately proceed to close the account so a fresh annual fee cycle does not begin the following year. If you believe you were never informed about the annual fee at the time of issuance, raise this specifically with the bank, since misrepresentation of fees at the point of sale is a common and often successfully resolved dispute.
How to Close a Credit Card You Haven’t Used in a Long Time
Closing a dormant card correctly, rather than simply cutting it up or letting it lapse from inactivity, protects both your finances and your credit report. The general process across most Indian banks follows the same broad steps.
First, check your latest statement for any outstanding balance, including the annual fee itself, and pay it off in full. A closure request will typically be rejected outright if there is any pending balance, unbilled EMI, or unresolved interest charge on the account. Next, cancel or update any standing instructions, auto-debits or subscriptions linked to that card, since these will otherwise continue to generate new charges even after you have requested closure, delaying the process further. Once the balance is clear, contact the bank through its official customer care number, net banking portal, or a written request, and explicitly ask for the credit card account to be closed, not merely the physical card blocked, since these are treated differently by most banks. Most banks process a closure request within 7 to 15 working days.
Once the closure is confirmed, insist on a written confirmation, typically a “No Objection Certificate” or closure confirmation letter, stating that the account has a nil balance and has been closed. Keep this document safely, since it is your proof if the account is ever incorrectly shown as active or overdue on a future credit report. Finally, check your credit report about 30 to 45 days after closure to confirm the account status has been correctly updated to “closed” rather than still appearing active or, worse, delinquent.
Credit Card Closure Checklist
| Step | What to Do | Why It Matters |
|---|---|---|
| Clear outstanding dues | Pay off any pending balance, including the annual fee | Closure requests are rejected if any balance remains |
| Cancel auto-debits and subscriptions | Remove the card from all linked recurring payments | Prevents new charges from being generated after your request |
| Submit a formal closure request | Call customer care or write in, asking to close the account, not just block the card | Blocking a card does not close the account or stop future fees |
| Get written confirmation | Ask for a closure letter or NOC confirming nil balance | Your proof of closure if disputes arise later |
| Check your credit report | Verify the account shows as “closed” after 30-45 days | Confirms the bank reported the closure correctly to bureaus |
| Redeem reward points first | Use or transfer points before submitting the closure request | Most issuers forfeit unredeemed points once the account is closed |
What Happens to Reward Points When You Close a Credit Card
This is the part most cardholders overlook, and it is worth planning for before you request closure, not after. Reward points earned on a credit card are managed by the card issuer’s own loyalty program, not by an independent account you control, and they are almost always non-transferable, meaning they cannot be moved to another person or even to a different card with the same bank.
Once a credit card account is closed, any unredeemed reward points are typically forfeited. Some banks provide a short grace period, commonly anywhere from a few days to around 30 days after the closure request, during which you can still redeem accumulated points for vouchers, merchandise, statement credit or other catalogue options, but once that window lapses, the points are void permanently. Any progress toward annual spend milestones or bonus thresholds is also generally lost the moment the account closes.
The straightforward takeaway is to redeem or use your reward points before you initiate closure, not after. Log into your card’s rewards portal, check your points balance and the redemption catalogue, and use them for whatever has the best value to you, whether that is a gift voucher, a bill credit, or merchandise, before you submit your closure request.
Common Mistakes People Make With Unused Credit Cards
A frequent mistake is assuming that not using a card means it cannot generate any real financial consequence, when an inactive card with an unpaid annual fee behaves exactly like an active card with any other unpaid bill for reporting purposes. Another common mistake is confusing “blocking” a card with “closing” the account, since a blocked card can still accrue an annual fee and interest even though it can no longer be swiped. People also tend to close a card in a rush after a dispute over fees, only to remember the unredeemed reward points afterward, by which point they are typically already forfeited. Finally, many cardholders never request written confirmation of closure, which becomes a real problem months later if the account resurfaces as active or overdue due to an internal bank error.
My Take
The pattern in almost every version of this problem is the same: the annual fee itself is rarely the real issue, the silence around it is. Banks are not particularly aggressive about proactively telling you that an unpaid fee is quietly accumulating finance charges and heading toward a bureau report, so the responsibility sits with the cardholder to act within the first billing cycle rather than several months later.
If you are holding a card you genuinely do not use, the cheapest path is almost always to resolve it immediately, either by getting the fee waived through a simple customer care call, or by paying it off and formally closing the account the same month. The reward points question is the one detail that is easy to forget in the moment, and it is worth the two minutes it takes to check your redemption catalogue before you make that closure call, since points earned over a year or more of spending are not worth losing over an oversight.
Frequently Asked Questions
1. Does an annual fee get charged even if I never use my credit card? Yes. Most Indian credit cards charge an annual fee automatically once the card is issued and activated, regardless of usage, unless the card is explicitly marked as lifetime-free.
2. Will an unpaid annual fee directly lower my CIBIL score? The unpaid fee itself does not directly lower your score, but if it remains unpaid past the due date and the account is reported as overdue or delinquent to credit bureaus, your score can be negatively affected.
3. Can I get an annual fee waived on a card I don’t use? Often, yes. Many banks will waive the annual fee on request, particularly for long-standing customers with a clean payment history, so it is always worth calling customer care before paying or disputing it.
4. What is the difference between blocking a credit card and closing it? Blocking prevents the card from being used for transactions, but the account and any associated fees can remain active. Closing the account formally ends the relationship and stops future annual fee charges.
5. How long does it take to close a credit card in India? Most banks process a closure request within 7 to 15 working days, provided there is no outstanding balance on the account.
6. Will closing a credit card hurt my credit score? Closing a card in good standing, with no outstanding dues, generally has a limited effect on your score, though it can slightly affect your credit utilisation ratio and the length of your credit history if it was an old account.
7. What happens to my reward points if I close my credit card? Unredeemed reward points are typically forfeited once the account is closed. Some banks offer a short grace period, often up to 30 days, to redeem points before they lapse permanently.
8. Can reward points be transferred to another credit card or person? No. Reward points are generally non-transferable, both to another individual and to a different card, even one issued by the same bank.
9. What should I do before requesting a credit card closure? Pay off any outstanding balance, cancel linked auto-debits and subscriptions, and redeem any unused reward points, before submitting the formal closure request.
10. How can I confirm my card has actually been closed? Request a written closure confirmation or No Objection Certificate from the bank, and check your credit report about 30 to 45 days later to verify the account status shows as “closed.”
Disclaimer
This article is for general informational purposes only and does not constitute financial or legal advice. Specific fee amounts, waiver policies, closure timelines and reward point rules vary by bank and by individual cardholder agreement. Readers should verify current terms directly with their card issuer and refer to their credit report through an authorised credit bureau before making decisions based on this content. FinanceChecks.com is not affiliated with any bank or credit bureau mentioned in this article.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.