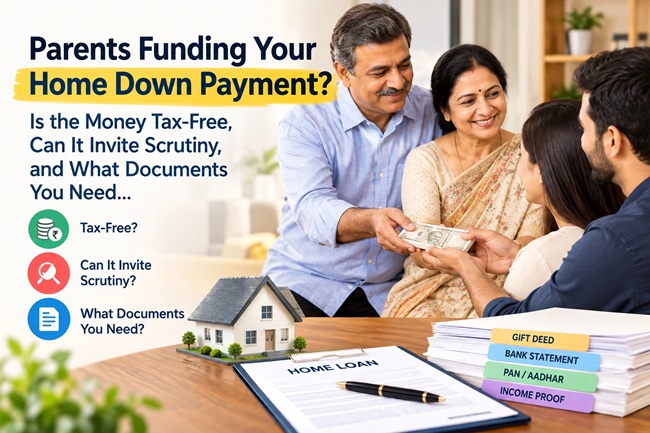
Parents Funding Your Home Down Payment? Is the Money Tax-Free, Can It Invite Scrutiny, and What Documents You Need

By the FinanceChecks.com Editorial Team | Published October 10, 2026 | Last reviewed October 10, 2026 | 10-minute read
For a growing number of young Indian buyers, the down payment is the hardest part of buying a home. Property prices keep climbing, savings grow more slowly, and the bank will still not lend the full amount. So the conversation at home often ends with a parent saying, “We will help you with the down payment.” It is a generous offer, and it comes with three practical worries. Will the money be taxed? Will the tax department ask questions? And what paperwork keeps everyone safe?
The short version is reassuring. Money from your parents is generally tax-free in your hands, with no upper limit. The longer version is where families get into trouble, because the tax exemption depends on the transaction being genuine and properly documented, and a few avoidable mistakes can turn a simple gift into a tax notice. This guide walks through each worry in order.
Quick Answer
Money received from your parents as a gift is exempt from income tax in your hands, with no cap on the amount, because parents fall within the legal definition of a “relative” for gift purposes. India has no gift tax on the person giving the money. The exemption was carried over into the Income-tax Act, 2025, which applies from April 1, 2026. Scrutiny usually arises not from the gift itself but from the paper trail around it: cash transfers, an unexplained source of your parents’ money, or a property value that looks large compared with your declared income. To stay clean, move the money through bank accounts, sign a simple gift declaration, keep your parents’ bank statements and proof of where the money came from, and keep everything together in case a bank or the tax department asks.
About This Guide
This guide was compiled by the FinanceChecks.com editorial team using the gift provisions of the Income-tax Act, 1961 (Section 56(2)(x)) and the Income-tax Act, 2025, the cash transaction restrictions in the Act, RBI’s loan-to-value norms for housing loans, and commentary from tax and legal publishers. Tax law was renumbered in the new Act, and section numbers change even where the rule stays the same, so we describe the rules by what they do. This is general information, and a chartered accountant can confirm how it applies to your family’s facts.
Is the Money Actually Tax-Free?
Yes, for a gift from a relative. In general, when an individual receives money or property without paying for it, and the total in a year exceeds ₹50,000, the amount is taxed as income in the receiver’s hands. That rule has an important exception: gifts from a “relative” are exempt entirely, whatever the amount. India abolished the old Gift Tax Act in 1998, so there is no tax for the person giving either.
Who counts as a relative matters more than most people realise, because the list is fixed in law and does not simply mean “family.”
| Giver | Counts as a relative? | Tax on the gift |
|---|---|---|
| Your parents | Yes | Exempt, no limit |
| Your spouse’s parents | Yes | Exempt, no limit |
| Your grandparents | Yes | Exempt, no limit |
| Your brother or sister | Yes | Exempt, no limit |
| Your parent’s brother or sister (uncle or aunt) | Yes | Exempt, no limit |
| Your spouse’s brother or sister | Yes | Exempt, no limit |
| Cousins | No | Taxable if the year’s total exceeds ₹50,000 |
| Friends and colleagues | No | Taxable if the year’s total exceeds ₹50,000 |
The residence of the giver does not change this. A parent who lives abroad is still a relative, so an NRI parent’s gift is exempt in your hands as well.
Two cautions apply. The exemption covers the gift itself, not the income the money later earns, which is taxed as usual, and it applies to genuine gifts, which is where the paper trail becomes important.
Can It Invite Scrutiny?
It can, and it helps to understand why. A tax officer looking at a home purchase is usually not worried about the gift being taxable. The questions are whether the money really came from your parents, whether they could afford it, and whether the transaction is genuine. Tax professionals often describe this as proving the giver’s identity, the giver’s capacity and the genuineness of the transaction.
Several things commonly draw attention.
A mismatch between your income and the property. Property purchases above certain values are reported to the tax department by the sub-registrar, and banks report large cash deposits. If your income tax return shows modest earnings and the property is large, a query asking how you funded it is not surprising. A documented gift answers it quickly.
Cash. Cash is the biggest risk factor. A person generally cannot receive ₹2 lakh or more in cash in a day or for a single event, and the penalty can equal the entire amount received. Taking cash for a property deal can also run into the restrictions on cash advances for immovable property and on cash loans of ₹20,000 or more. Most experts read these rules as covering family transfers too, so moving a large sum in cash from parent to child is the single most avoidable mistake.
An unexplained source on your parents’ side. If your parents cannot show where the money came from, for example a withdrawal that does not match any known savings, the tax department can question their source. Unexplained money is taxed at a very high flat rate in the hands of whoever cannot explain it, and in some cases the dispute spills over to the recipient.
Several unrelated transfers. Money arriving from many different people, or from non-relatives, can be taxable above the ₹50,000 limit and looks more complicated than a clean transfer from two parents.
You May Also Like To Read About:
- Daughter vs Son Property Rights in India: Every Scenario Compared
- You Paid for Property Construction, But the House Is in Your Mother’s Name: Do Your Siblings Have Equal Rights?
- Bank Lost Your Property Documents? Here’s the Legal Process to Get Justice
- Sold Inherited Property in India? Here’s Who Pays the Tax, and How Much You Can Legally Save
- Primary Owner vs Co-Owner vs Co-Borrower on a Home Loan: What Each Term Actually Means Legally
The Documents That Keep You Safe
You do not need an elaborate legal file, but you do need the right pieces in one place. Banks that finance your home loan also tend to ask for proof of where the down payment comes from, so the same file serves two purposes.
| Document | Who provides it | Why it matters |
|---|---|---|
| Gift deed or signed gift declaration | Your parents | States the amount, the relationship, the date and that it is a gift with no repayment |
| Bank statement showing the transfer from your parents’ account | Your parents’ bank | Proves the money moved through banking channels |
| Your bank statement showing the credit | Your bank | Completes the trail from donor to you |
| Proof of your parents’ source of funds | Your parents | Shows they had the money, such as savings, a maturing fixed deposit, retirement benefits or sale proceeds |
| Your parents’ PAN and ID details | Your parents | Identifies the giver |
| Income tax returns of your parents | Your parents | Supports their capacity to give |
| Home loan sanction letter, builder receipts and registered agreement | You | Links the money to the property purchase |
A gift of money does not strictly need a registered deed in the way a gift of property does, and stamp duty treatment varies by state, but a signed declaration, ideally notarised, is a small effort that settles most questions later.
Gift, Loan or Co-Ownership: Which Route Should Parents Take?
Parents who want to help have three realistic options, and each has different tax and family consequences.
| Route | Tax effect | Paperwork | Main risk |
|---|---|---|---|
| Outright gift | Exempt for you; no gift tax on the parents | Gift declaration and bank trail | Parents give up the money for good |
| Loan from parents | No tax on the principal; interest you pay is taxable income for your parents | Written loan agreement and bank repayments; cash loans of ₹20,000 or more are restricted | Repayment pressure and disputes if terms are vague |
| Parents as co-owners | Depends on ownership and contribution | Names on the sale deed and loan documents | Shared ownership brings inheritance and sibling questions |
For most families the gift is the cleanest option. The loan fits when parents want the money back or when they have other children and want to be fair about it. Co-ownership solves the “whose house is it” question but creates new ones, which we cover in our guides to primary owner versus co-owner and to siblings’ rights over a house in a parent’s name.
A Clean Step-by-Step Process
A simple sequence keeps the transaction easy to explain.
First, decide the route with your parents and talk to your siblings if the gift is large, since family friction can be harder to fix than any tax problem. Second, have the money move from your parents’ bank account into your own account, instead of paying the builder directly, because this makes you the clear owner of the funds. Third, sign the gift declaration on the same date as the transfer. Fourth, gather your parents’ proof of source, such as the statement for the fixed deposit that matured or the sale papers for an asset they sold. Fifth, pay the seller or builder from your own account and keep the receipts. Sixth, store everything together, with digital copies, for at least as long as a tax notice could arrive.
Paying the builder directly from your parents’ account is not forbidden, and the benami law has a specific allowance for property bought in a child’s name with a parent’s known funds, but routing the gift through your account is simpler to prove.
How Much Down Payment Do You Actually Need?
RBI’s loan-to-value limits set the minimum you must bring yourself. For individual housing loans, lenders can generally finance up to 90% of the property value for loans up to ₹30 lakh, up to 80% for loans between ₹30 lakh and ₹75 lakh, and up to 75% above ₹75 lakh, which means a minimum down payment of 10%, 20% or 25% respectively. Stamp duty, registration and other costs usually come on top, and lenders typically do not finance them. If the property costs ₹50 lakh or more, the buyer is also generally required to deduct 1% TDS from the payment to the seller, which is another reason to plan the cash needed with some margin.
The Parents’ Side, Which Is Often Forgotten
Gifting money does not create a tax bill for parents, but how they raise the money can. If they sell shares, mutual fund units or a property to fund the gift, capital gains tax applies to them as usual, and breaking a fixed deposit early may reduce what they earn. These are worth planning before the transfer.
The more important point is their own security. Retired parents who hand over a large share of their savings can leave themselves short of income for medical bills and daily life, and they have no easy way to rebuild it. A good rule is that parents should keep enough to cover their own expenses and emergencies for the rest of their lives before they gift anything.
What About Home Loan Tax Benefits?
The down payment itself does not earn a deduction. Tax benefits relate to the home loan’s interest and principal that you pay, and they depend on your tax regime, because many of these deductions are available only under the old regime. They also generally go to the person who both owns the property and pays the loan, so if your parents pay your EMI directly to the lender, claiming the deduction can become a debate. If your parents want to help with EMIs too, route the money into your account as a gift first and make the payment yourself.
Common Mistakes Families Make
The most common mistake is moving the money in cash, which risks the penalty for cash receipts and leaves no proof. Another is treating the transaction as informal because it is between family, with no declaration and no record of the parents’ source of funds. Families also pay the builder directly from the parents’ account, which weakens the paper trail, or mix gift and loan, so no one remembers whether the money is to be repaid. Some parents fund the gift by breaking investments without checking the capital gains consequences. And some gift so much that their own retirement security suffers.
My Take
What stands out is how little the law asks of families who do this properly and how much trouble it causes for those who do not. The tax rule is generous, with no cap and no tax for the parents, and the risk comes almost entirely from informality. A bank transfer, a one-page declaration and a folder of statements turn a stressful notice into a ten-minute reply.
The part I would give the most thought to is the family conversation, not the tax. Money from parents often carries unspoken expectations, such as whether it is a gift or an advance on inheritance, and whether siblings are being treated fairly. Settling those questions out loud, and writing the answer down, is as valuable as any document on the checklist.
Frequently Asked Questions
1. Is money from parents for a home down payment taxable in India? No. A gift from parents is exempt from income tax in your hands because parents are relatives under the law, and there is no upper limit on the amount.
2. Is there any limit on how much parents can gift? There is no monetary limit on gifts from relatives. The practical limits are your parents’ own financial security and the need to document the gift properly.
3. Do my parents pay tax for gifting me money? India has no gift tax on the giver. However, if they sell investments or property to raise the money, capital gains tax can apply to them on that sale.
4. Do we need a gift deed? A registered gift deed is not strictly required for a gift of money, but a signed gift declaration with the amount, relationship, date and a statement that no repayment is expected is strongly advised. Stamp duty treatment varies by state.
5. Can the tax department question a gift from my parents? It can, usually to check where the money came from and whether the transaction is genuine. A bank transfer, a declaration and proof of your parents’ source of funds typically answer these questions.
6. Can my parents give the money in cash? It is risky. A person generally cannot receive ₹2 lakh or more in cash in a day, and the penalty can equal the amount received. Use bank transfers.
7. Are my parents-in-law also relatives for this purpose? Yes. Parents of your spouse are within the definition of a relative, so their gift is exempt as well.
8. What if my parents live abroad? A gift from a parent who is a non-resident is still exempt as a gift from a relative. Use banking channels and keep the remittance records.
9. Can my parents pay the builder directly? It can be done, but a direct payment weakens your paper trail. Moving the money to your account first and paying the builder yourself is cleaner.
10. Can I claim a home loan deduction on money my parents funded? The down payment itself earns no deduction. Deductions relate to interest and principal paid on the loan, depend on your tax regime, and generally go to the owner who pays, so confirm your situation with a tax professional.
How We Verified This Information
This guide was researched using the gift provisions of the Income-tax Act, 1961 and the Income-tax Act, 2025, the cash receipt and cash loan restrictions, RBI’s loan-to-value norms for housing loans, and commentary from several tax and legal publishers. Published commentary places the relatives exemption in Section 92 of the Income-tax Act, 2025, but section numbers can differ across sources, so we describe the rule by its effect. Thresholds and numbering can change, and we recommend confirming current figures with a chartered accountant.
Disclaimer
This article is for general informational purposes only and does not constitute tax, legal or financial advice. Tax provisions, reporting thresholds and loan-to-value norms are subject to change, and your own situation may differ. Readers should consult a chartered accountant or tax professional before relying on any gift, loan or ownership structure for a property purchase. FinanceChecks.com is not a tax advisory firm.
Last reviewed and fact-checked on October 10, 2026 by the FinanceChecks.com Editorial Team.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.