You Can Sell One House and Buy Several — And Still Keep Your Tax Exemption? Here’s the Ruling That Proves It

Picture this. You finally sell that one property you’ve held for years. The sale value comes in at a jaw-dropping ₹23.76 crore. You’re relieved, maybe even a little proud of the decision. And then, almost immediately, a new problem lands on your desk — the taxman wants his share of the capital gains, and he isn’t in the mood to be generous about how you reinvest that money.
This is exactly what happened to a taxpayer whose case recently went all the way to the Income Tax Appellate Tribunal, or ITAT. And the outcome of that case is something every homeowner, property investor, and anyone even remotely thinking of selling a house in India should sit up and pay attention to.
Because here’s the thing — most of us assume the rules around capital gains tax are rigid, black-and-white, take-it-or-leave-it. Sell a house, buy exactly one house, claim your exemption, done. But real life is rarely that tidy. People sell one big property and split the money into two, three, sometimes more homes — for their kids, for diversification, for practical family reasons. So what happens to your tax exemption when you do that? This case answers that question, and the answer might surprise you.
What Actually Happened in This Case
Let’s break down the story in plain language, without the legal jargon that usually makes these judgments unreadable.
A taxpayer sold a residential property for ₹23.76 crore. Under the Income Tax Act, when you sell a house you’ve held for the long term, you earn what’s called a long-term capital gain — and that gain is taxable, unless you reinvest it in another residential house within the time limits the law allows.
That’s where Section 54 of the Income Tax Act comes in. This is the provision that lets you claim exemption on capital gains from selling a residential house, as long as you plough that money back into another residential property — either buying one within one year before or two years after the sale, or constructing one within three years.
Now, out of the total proceeds, the taxpayer deposited ₹8.43 crore into something called the Capital Gains Account Scheme, or CGAS. This scheme exists precisely for situations where you haven’t finalised your new property purchase before your income tax return filing deadline. Instead of losing your exemption because you couldn’t close the deal in time, you park the unutilised amount in a designated bank account under CGAS, and you get a window to use it later for buying or constructing your new home.
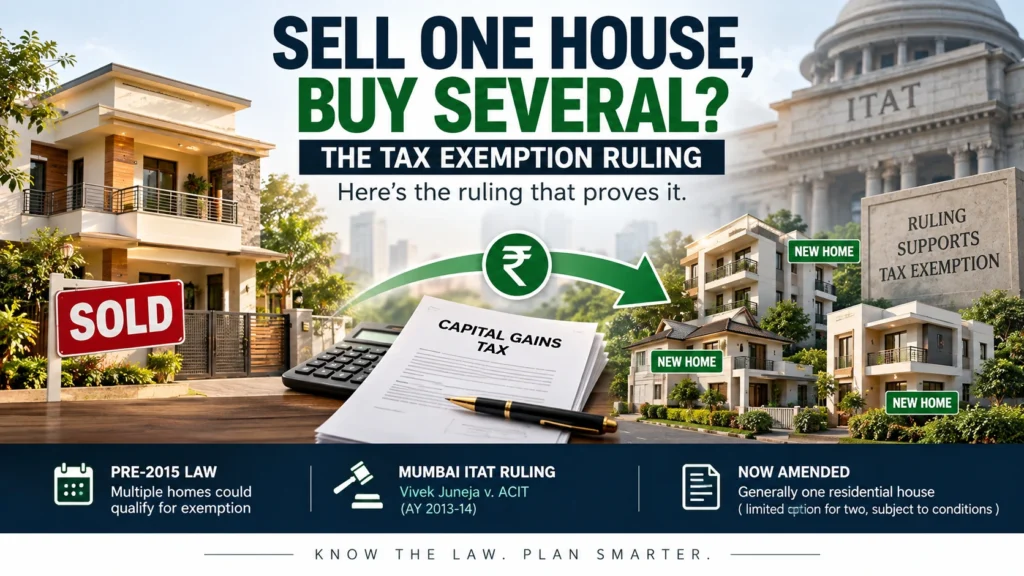
The taxpayer then went on to invest the capital gains — including money drawn from that CGAS account — into more than one residential property. And this is exactly where the Assessing Officer stepped in and objected. The tax department’s stand was familiar and, frankly, one that trips up thousands of taxpayers every year: that Section 54 exemption is meant for reinvestment in a single house, not multiple ones, and that claiming exemption across several properties simply isn’t allowed.
The matter escalated, and it eventually reached the ITAT. And the Tribunal’s ruling went in favour of the taxpayer, holding that the exemption could not be denied simply because the reinvestment was spread across more than one residential property. The CGAS deposit of ₹8.43 crore played a crucial role in supporting the taxpayer’s position, because it demonstrated genuine intent and compliance — the money wasn’t sitting idle or being misused, it was parked exactly the way the law expects, waiting to be deployed into residential property.
Why This Ruling Matters More Than It Seems
If you’ve ever read Section 54 casually, you’d probably walk away thinking it strictly limits you to one new house. And for a long time, that’s how many Assessing Officers interpreted it too — rigidly, almost defensively, as if any deviation was an attempt to dodge tax.
But Tribunals across the country, including in this case, have increasingly taken a more practical view. The reasoning goes something like this — the law was written to encourage reinvestment in residential property, not to punish taxpayers for the specific number of units they choose to buy, especially when the underlying intent and the paper trail are clean.
This distinction matters enormously if you’re someone who sells an ancestral property, a large family home, or a high-value asset and then decides to split the proceeds — say, one flat for yourself and one for your child, or two units in the same building for a joint family. Under a narrow reading of the law, you’d risk losing a large chunk of your exemption. Under the more taxpayer-friendly reading that Tribunals like the ITAT have been applying, that risk shrinks considerably, provided you’ve followed the procedural requirements properly.
The Real Lesson Isn’t Just About Multiple Houses — It’s About Doing Things Right
Here’s what a lot of people miss when they hear about a case like this. The headline is “multiple houses allowed,” but the real hero of this story is procedure. The taxpayer won largely because the money trail was clean and well-documented — the unutilised capital gains were deposited into the Capital Gains Account Scheme exactly as the law requires, well before the return filing deadline.
That single step — depositing unused sale proceeds into CGAS on time — is often the difference between a smooth exemption claim and a prolonged fight with the tax department. Too many taxpayers either forget about CGAS entirely, or delay the deposit past the due date, and then find themselves arguing technicalities in front of an Assessing Officer who isn’t inclined to be sympathetic.
So if there’s one takeaway to carry forward from this ₹23.76 crore story, it’s this — the exemption isn’t automatically yours just because you eventually bought residential property with the money. It’s yours because you followed the process, kept the paperwork clean, and gave the tax department no real reason to question your intent.
What Should You Actually Do If You’re Planning to Sell Property and Reinvest
If you’re staring down a similar situation — a big property sale on the horizon, and a plan to reinvest across more than one home — here’s a practical way to think about it.
Know your timelines cold. You get one year before the sale, or two years after, to purchase a new residential house, and three years if you’re constructing one. Miss these windows and the exemption simply isn’t available, no matter how good your intentions were.
Don’t sit on unused money past your filing deadline. If you haven’t finalised your new property purchase before you file your income tax return, deposit the unutilised capital gains into the Capital Gains Account Scheme through an authorised bank. This one step alone protects your exemption and gives you breathing room to finalise your purchase later.
Understand the ₹2 crore threshold for two houses. The law allows exemption on investment in two residential houses only if your total capital gains don’t exceed ₹2 crore, and this option can be used only once in your lifetime. Beyond ₹2 crore in gains, the traditional reading restricts you to one house — although, as this case shows, Tribunals have sometimes taken a broader view depending on the specific facts.
Keep every document. Sale deed, purchase agreements, bank statements showing fund transfers, CGAS deposit receipts — all of it. If your case is ever scrutinised, this paper trail is what separates a taxpayer who wins at appeal from one who doesn’t.
Talk to a chartered accountant before you sell, not after. Every property sale is different — the value, the number of properties you already own, whether it’s a long-term or short-term asset, family arrangements, and so on. A ten-minute conversation before you sign the sale deed can save you months of litigation later.
A Quick Reality Check
It’s worth being honest here — this ruling doesn’t mean every taxpayer who splits capital gains across five properties will automatically win at the Tribunal. Every case turns on its own facts. The amounts involved, whether the deposits were made on time, whether the new properties genuinely qualify as residential houses, and how convincingly the taxpayer can demonstrate intent — all of this shapes the outcome. Tax rulings from Tribunals are also not always uniform, and the department can, and sometimes does, appeal further to higher courts.
So treat this case as an encouraging data point and a lesson in doing things correctly — not as a blanket guarantee that the law will bend your way.
Frequently Asked Questions
1. What is Section 54 of the Income Tax Act? Section 54 allows individuals and Hindu Undivided Families to claim exemption on long-term capital gains earned from selling a residential house, provided the gains are reinvested in another residential property in India within the prescribed time limits.
2. Can I claim Section 54 exemption if I buy more than one house with my capital gains? Traditionally, the law and many tax officers have restricted this to one residential house, except where total capital gains don’t exceed ₹2 crore, in which case two houses are allowed once in a lifetime. However, recent Tribunal rulings, including this ₹23.76 crore case, have shown that exemption for multiple properties can be allowed depending on the specific facts, documentation, and genuine intent behind the investment.
3. What is the Capital Gains Account Scheme, and why does it matter? CGAS is a scheme that lets you park unutilised capital gains in a designated bank account if you haven’t finalised your new property purchase before filing your income tax return. Depositing money here on time protects your exemption claim and gives you extra time to complete your purchase or construction.
4. What is the time limit to buy or construct a new house under Section 54? You can purchase a new residential house within one year before or two years after the sale of your old property, or construct a new house within three years from the date of sale.
5. Is there a maximum limit on the Section 54 exemption amount? Yes. Since the Finance Act 2023 changes, the maximum exemption under Section 54 is capped at ₹10 crore, even if your reinvestment exceeds that amount.
6. What happens if I don’t deposit unused capital gains into CGAS before filing my return? You risk losing the exemption on that unutilised portion, because the law expects you to either invest the money in a qualifying property or park it in CGAS by the return filing due date. Some Tribunals have shown leniency where the property was eventually purchased within the overall time limit, but this isn’t guaranteed, so it’s best not to rely on that leniency.
7. Does owning multiple floors in the same building count as owning multiple houses? Several rulings, including cases involving properties in Delhi and Mumbai, have held that multiple floors in a single building can be treated as one residential house for exemption purposes, rather than being counted as separate properties. This is a distinct question from buying entirely separate flats or houses in different locations.
8. Should I consult a professional before selling a high-value property? Absolutely. Capital gains tax planning depends heavily on your specific circumstances — how long you’ve held the property, how many other houses you own, your reinvestment plan, and your overall financial goals. A qualified chartered accountant or tax advisor can help you structure the transaction in a way that’s both compliant and tax-efficient.
9. Can this ITAT ruling be challenged further? Yes. Tribunal rulings can be appealed to the High Court and further to the Supreme Court by either the taxpayer or the tax department. Until a higher court settles the question definitively, interpretations can continue to vary across different Tribunal benches and jurisdictions.
Disclaimer
This article is written purely for general informational and educational purposes and is based on publicly reported details of an income tax tribunal ruling. It does not constitute legal, financial, or tax advice, and it should not be relied upon as a substitute for professional consultation. Tax laws, exemption limits, and judicial interpretations are subject to change and can vary based on individual facts and circumstances. Readers are strongly advised to consult a qualified chartered accountant, tax practitioner, or legal professional before making any decisions related to property sales, capital gains, or tax exemptions. The author and publisher accept no liability for any loss or consequence arising from actions taken based on the information presented in this article.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.