
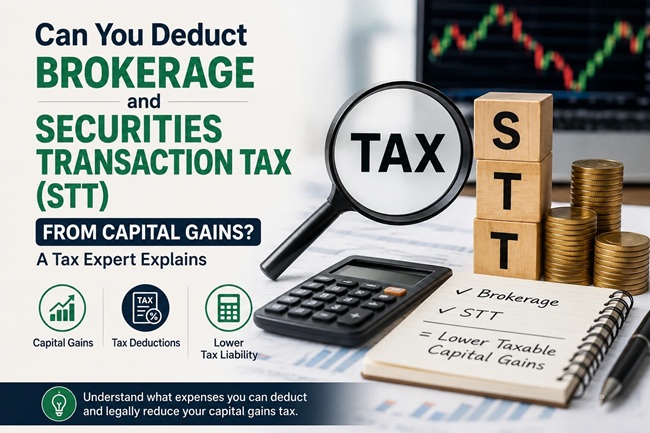
Can You Deduct Brokerage and Securities Transaction Tax (STT) From Capital Gains? A Tax Expert Explains

Vikram sold a batch of shares last year, made what looked like a healthy profit on his contract note, and sat down to calculate his tax by simply subtracting his purchase cost from his sale price. It felt straightforward enough, until his CA asked him a question he hadn’t considered at all: had he deducted his brokerage? And what about the STT he’d paid on both the buy and the sell side? Vikram assumed both were just costs of doing business that obviously reduced his taxable gain. He was half right, and the half he got wrong is exactly where most retail investors trip up.
This is a genuinely common point of confusion, and it matters more than it might seem, because brokerage and STT sound like they belong in the same bucket, transaction costs paid to execute a trade, when the tax law actually treats them in completely opposite ways.
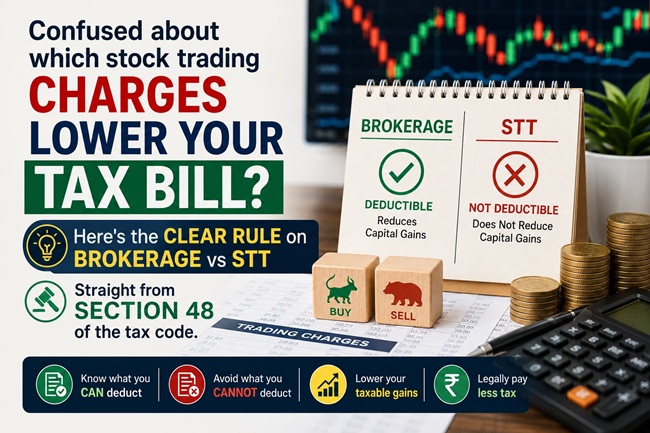
Quick answer: Brokerage can be deducted from your capital gains, since it qualifies as a transfer expense under Section 48 of the Income Tax Act. STT, the Securities Transaction Tax, cannot be deducted, since Section 40(a)(ib) specifically disallows it as an expense while computing capital gains. The reasoning behind this distinction is that STT already earns you a benefit elsewhere, it’s what qualifies your equity gains for the lower, concessional tax rates under Sections 111A and 112A in the first place, so the law doesn’t let you claim it twice.
About This Guide: Written by the Finance Checks Editorial Team, Personal Finance Researchers. This article reflects Section 48 and Section 40(a)(ib) of the Income Tax Act as applicable for FY 2025-26 (AY 2026-27), along with standard practice followed in computing capital gains on listed securities. Last updated: August 2026.
The Basic Formula Behind Every Capital Gains Calculation
Every capital gains calculation in India, whether for stocks, mutual funds, property, or any other capital asset, starts from the same foundation laid out in Section 48 of the Income Tax Act. Your capital gain equals your sale value, minus your cost of acquisition, minus any expenditure incurred wholly and exclusively in connection with the transfer. That last piece, “expenditure incurred wholly and exclusively in connection with the transfer,” is the specific clause that decides which charges you’re allowed to subtract from your gain, and it’s exactly where the brokerage-versus-STT distinction plays out.
Why Brokerage Is Deductible
Brokerage is the fee your broker charges for actually executing your buy and sell orders. Since this cost is incurred specifically and directly because of the transfer of your shares, it fits squarely within Section 48’s definition of a transfer expense. This treatment is well-established, supported by both standard tax practice and judicial precedent, and applies to brokerage paid on both the purchase side and the sale side of a transaction.
In practice, this means the brokerage you paid when you originally bought the shares gets added to your cost of acquisition, effectively raising your purchase cost slightly, while the brokerage you pay when you sell gets subtracted directly from your sale value. Either way, both legs of brokerage genuinely reduce your final taxable capital gain.
Other charges bundled into the same “transfer expense” category, alongside brokerage, include stamp duty, registration fees, legal expenses, and exchange transaction charges levied by the NSE or BSE, all of which are similarly deductible since they’re directly and necessarily incurred as part of completing the trade.
Why STT Is Not Deductible, Even Though It Feels Identical to Brokerage
This is the part that genuinely surprises most people, because from a purely practical standpoint, STT looks exactly like brokerage, a charge quietly deducted on your contract note every time you buy or sell. But Section 40(a)(ib) of the Income Tax Act specifically and explicitly disallows STT as a deduction while computing capital gains. This isn’t an oversight or an inconsistency in the law, it’s a deliberate design choice, and understanding why makes the rule much easier to remember.
STT already buys you something valuable elsewhere in the tax code. The concessional capital gains rates that apply to listed equity shares and equity mutual funds, the 20% short-term rate under Section 111A and the 12.5% long-term rate under Section 112A, both specifically require that STT has been paid on the transaction as a condition for accessing those lower rates in the first place. If STT were also allowed as a deductible expense on top of that, you’d effectively be getting the benefit of the concessional rate and a further deduction for the very payment that qualified you for it, which the law deliberately prevents by disallowing the deduction outright.
A Worked Example to Make This Concrete
Suppose you bought 100 shares of a company at ₹500 each, paying ₹50,000 in total, along with ₹100 in brokerage and ₹15 in STT on the purchase. You later sold those same shares at ₹600 each, receiving ₹60,000, and paid another ₹120 in brokerage and ₹18 in STT on the sale.
Your cost of acquisition becomes ₹50,000 plus the ₹100 purchase-side brokerage, working out to ₹50,100. Your net sale value becomes ₹60,000 minus the ₹120 sale-side brokerage, working out to ₹59,880. Your taxable capital gain is the difference between these two figures, ₹59,880 minus ₹50,100, which comes to ₹9,780. Notice that neither the ₹15 nor the ₹18 paid as STT features anywhere in this calculation at all, since both amounts are simply disallowed and don’t reduce your gain in any way, even though they appeared right there on your contract note alongside the brokerage that did count.
What About Other Common Trading Charges?
Beyond brokerage and STT, your contract note typically includes a handful of other charges, and it’s worth knowing where each one falls.
- Exchange transaction charges, levied by the NSE or BSE for facilitating the trade, are directly linked to the transfer and are generally treated as deductible, similar to brokerage.
- Demat account charges, including annual maintenance fees, generally aren’t treated as expenses directly connected to a specific transfer, since they’re ongoing account-holding costs rather than a charge tied to any individual buy or sell transaction, and are typically not deductible against a specific capital gains calculation.
- GST charged on your brokerage is usually treated consistently with the brokerage itself, since it’s a direct additional cost of the same service, and is generally included as part of the deductible transfer expense.
- Internet, phone, or other general costs you personally incur while trading, however genuinely related they feel to your trading activity, are not treated as transfer expenses under Section 48, since they aren’t incurred specifically and exclusively in connection with a particular transfer, and claiming these as capital gains deductions is a mistake that has led to scrutiny notices for some taxpayers who tried it.
Where to Actually Find These Figures
Every trade you make generates a contract note from your broker, which itemizes brokerage, STT, exchange charges, GST, and any other applicable fees separately for that specific transaction. Most brokers today also provide a consolidated tax P&L statement or capital gains statement covering the full financial year, which is genuinely the more practical document to work from when filing your return, since manually adding up individual contract notes across dozens or hundreds of trades is both tedious and more prone to error. It’s worth downloading this consolidated statement directly from your broker’s platform rather than reconstructing the numbers from memory or estimates.
Does This Distinction Apply the Same Way to Short-Term and Long-Term Gains?
Yes. The Section 48 formula, and the specific disallowance of STT under Section 40(a)(ib), applies uniformly regardless of whether your resulting gain is classified as short-term or long-term. What changes between short-term and long-term isn’t which expenses you’re allowed to deduct, that stays consistent, it’s simply the tax rate applied to the resulting net gain after those deductions, and whether any exemption threshold, like the ₹1.25 lakh annual exemption on long-term equity gains, applies to that final figure.
Common Mistakes People Make With This Calculation
The most frequent mistake, exactly like Vikram’s initial assumption, is treating STT identically to brokerage simply because both appear as line items on the same contract note, without realizing the law treats them in fundamentally opposite ways for this specific calculation.
Another common mistake is forgetting to include purchase-side brokerage in the cost of acquisition, focusing only on sale-side brokerage since that’s the transaction most directly associated with realizing the gain, and understating the true cost of acquisition as a result.
A third mistake is attempting to deduct genuinely unrelated costs, internet bills, a portion of a laptop’s cost, or general subscription services used for market research, none of which qualify as expenses incurred wholly and exclusively in connection with the specific transfer, and claiming them risks drawing exactly the kind of scrutiny that a straightforward, correctly computed return would otherwise avoid entirely.
My Take
The brokerage-versus-STT rule is one of those tax details that seems needlessly technical until you understand the logic behind it, and once you do, it stops feeling arbitrary. STT isn’t disallowed to be difficult, it’s disallowed because you’ve already been compensated for paying it through a meaningfully lower tax rate on the gain itself. If you’re calculating your own capital gains rather than relying entirely on your broker’s tax statement, the one habit worth building is treating every contract note line item as either “part of Section 48’s transfer expense” or “not,” rather than assuming everything labelled as a charge automatically reduces your tax.
Frequently Asked Questions
Can brokerage be deducted while calculating capital gains on shares? Yes. Brokerage paid on both the purchase and sale of shares qualifies as a transfer expense under Section 48 of the Income Tax Act and can be deducted while computing your capital gain.
Can STT be deducted from capital gains? No. Section 40(a)(ib) of the Income Tax Act specifically disallows STT (Securities Transaction Tax) as a deductible expense while computing capital gains, even though it appears as a charge on the same contract note as brokerage.
Why is STT not deductible if brokerage is? STT already provides a tax benefit elsewhere, it’s a required condition for accessing the concessional capital gains tax rates under Sections 111A and 112A for listed equity shares and equity mutual funds. Allowing it as a deduction on top of that concessional rate would effectively provide the benefit twice, which the law specifically prevents.
Are exchange transaction charges deductible from capital gains? Yes. Exchange transaction charges levied by the NSE or BSE are directly connected to executing the trade and are generally treated as deductible, similar to brokerage.
Can I deduct demat account maintenance charges from my capital gains? Generally, no. Demat account charges are treated as ongoing account-holding costs rather than an expense tied to a specific transfer, so they typically aren’t deductible against a particular capital gains calculation.
Is GST on brokerage deductible from capital gains? Yes. GST charged on brokerage is usually treated consistently with the brokerage itself, since it’s a direct additional cost of the same service, and is generally included as part of the deductible transfer expense.
Does the brokerage and STT rule apply differently to short-term versus long-term capital gains? No. The rule for which expenses are deductible remains the same regardless of whether the gain is short-term or long-term. What differs between the two is the applicable tax rate and any exemption threshold on the final net gain, not the expense deduction rules themselves.
Where can I find my brokerage and STT figures for tax filing? Your broker’s contract note itemizes these charges for each individual trade, but a consolidated tax P&L or capital gains statement, available on most broker platforms for the full financial year, is generally the more practical and accurate source for tax filing purposes.
Can I deduct internet or research subscription costs from my capital gains as a trading expense? No. These are general costs not incurred wholly and exclusively in connection with a specific transfer, and attempting to deduct them from capital gains isn’t permitted under Section 48 and can attract scrutiny.
Does this rule about STT apply to mutual funds too? Yes, the same principle applies to equity-oriented mutual fund units, where STT is paid on redemption. STT remains non-deductible under Section 40(a)(ib) while other genuine transfer-related expenses, where applicable, follow the same Section 48 treatment as with shares.
Disclaimer: This article is for general informational and educational purposes only and does not constitute tax or legal advice. Provisions under Sections 48 and 40(a)(ib) of the Income Tax Act are subject to interpretation and change. Please consult a qualified chartered accountant or tax professional for guidance specific to your capital gains calculations.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.

[…] then, almost immediately, a new problem lands on your desk — the taxman wants his share of the capital gains, and he isn’t in the mood to be generous about how you reinvest that […]