How to Manage Your SIP and Investments During a War, Natural Calamity or Market Crash: What to Do and How to Balance Your Portfolio

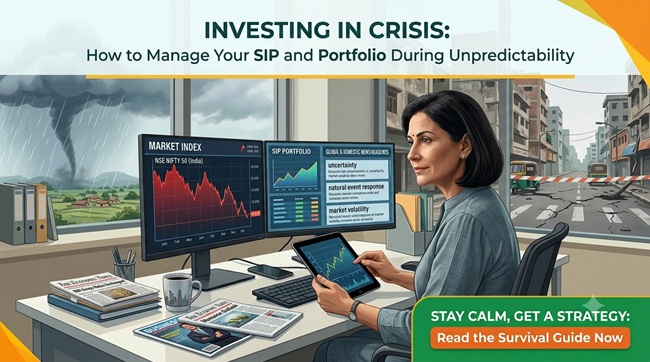
Markets do not fall politely. They fall on a Monday morning, with a headline about a war, an oil shock or a disaster, and by the afternoon your portfolio app is red and every message group is arguing about whether to stop SIPs. September 28, 2026 was one of those mornings: Indian benchmarks slipped, with the Nifty dropping below 23,100, as oil prices rose amid the seven-month-old conflict involving Iran, the United States and Israel and the disruption of a critical shipping lane. Foreign institutional investors were net sellers while domestic institutions kept buying.
Whether the trigger is a war, a natural calamity or a global shock, the right response follows the same logic. This guide explains what to do with your SIPs, how to protect money you will need soon, how to rebalance, what to avoid, and how to keep your finances steady when your own income or life is affected.
Quick Answer
If your SIP is meant for a goal more than five years away and your income is stable, the usual answer is to keep it running, because a SIP buys more units when prices are low and history shows that Indian equity markets have recovered from major crashes, though recovery time has ranged from months to a couple of years. Protect what you will need within the next three years by keeping it out of equity, hold an emergency fund of six to twelve months of expenses in liquid or low-risk instruments, rebalance back to your target asset allocation using fresh money before selling, and avoid panic redemptions, leverage and chasing news-driven bets. If a calamity hits your own income or home, prioritise emergency cash, insurance premiums and EMIs first, and pause or reduce SIPs rather than breaking long-term investments or the lock-in of tax-saving funds.
About This Guide
This guide was compiled by the FinanceChecks.com editorial team using current market reporting from September 2026, historical market episodes in India including the 2008 global financial crisis and the 2020 COVID crash, and standard asset allocation and risk management principles used in personal finance planning. This is educational content, not personalised advice: your age, income stability, goals and existing holdings determine what is right for you, and a SEBI registered investment adviser can help tailor a plan. We will update this guide as the current situation develops.
What Is Actually Happening in Markets Right Now
As of late September 2026, several forces are pressing on Indian markets at once. A prolonged conflict in the Middle East has disrupted oil flows through a key shipping route and pushed crude prices higher. India imports most of its oil, so higher crude raises the risk of inflation, a weaker rupee and a wider trade deficit. Global bond yields are elevated, foreign investors have been persistent sellers, and some brokerages have flagged the possibility of interest rate increases if oil stays high.
At the same time, domestic investors, largely through SIPs and mutual funds, have kept buying, which has cushioned the fall. This pattern of foreign selling and domestic buying has repeated across several past corrections, and it is one reason SIP discipline matters at the system level as well as for individual investors.
Nobody can say when the situation will resolve, and this guide does not attempt to predict it. The point is to build a plan that works whether the fall ends next month or continues for a year.
What History Says About Crashes and Recoveries
| Episode | What Happened | Approximate Recovery |
|---|---|---|
| 2008 global financial crisis | Sensex fell by more than half from its January 2008 peak | Roughly two years to regain the earlier high |
| 2020 COVID crash | Nifty fell roughly 38% in about two months | About eight months to regain its previous peak |
| Geopolitical shocks (various) | Sharp but often shorter corrections when the shock did not damage the economy | Varied, often months |
Past recoveries do not guarantee future ones, and a fall driven by a lasting economic shock can take longer. But the pattern is consistent: investors who kept buying through the fall and had a long horizon were rewarded, while investors who stopped SIPs or redeemed near the bottom locked in losses.
You May Also Like To Read About:
- SIP vs STP vs SWP: The Three Strategies Explained Together, and When to Use Each
- SIP Step-Up: Why Increasing Your SIP by Just 10% a Year Changes Everything
- SIP vs Gold vs Fixed Deposit: Where Should Your Next 10,000 Rupees Actually Go
- SIP vs PPF: Which One Actually Makes More Sense for You?
- SIP vs Lumpsum: The ₹5 Lakh Bonus Question Every Investor Gets Wrong
- SIP Calculator
Should You Stop Your SIP During a Crash?
The answer depends on your time horizon and your finances, not on the headline.
| Your Situation | What Usually Makes Sense |
|---|---|
| Goal is 7 or more years away and income is stable | Continue the SIP; falling prices mean more units per rupee |
| Goal is 3 to 5 years away | Continue, but review the equity share and start moving part of the goal money to safer funds |
| Goal is within 3 years | Keep this money out of equity; do not depend on markets for near-term needs |
| Income is disrupted (job loss, business hit, calamity) | Prioritise emergency cash, insurance and EMIs; pause or reduce the SIP rather than cancel it |
| You have surplus cash and a long horizon | Consider increasing the SIP or staggering extra investment over several months |
| You are retired and withdrawing | Protect two to three years of expenses in low-risk funds so you are not forced to sell equity at lows |
Here is a simple hypothetical illustration of why continuing can help. Imagine a ₹10,000 monthly SIP where the fund’s NAV moves from ₹100 to ₹80, then ₹70, then ₹90, then back to ₹100 over five months. You would buy about 100, 125, 143, 111 and 100 units, for a total of roughly 579 units at an average cost of about ₹86. When the NAV returns to ₹100, your ₹50,000 investment is worth about ₹57,900, a gain of nearly 16% even though the NAV ended exactly where it started. This is only an example with made-up numbers, and it does not mean SIPs always make money, but it shows how buying during a dip lowers the average cost.
Step 1: Separate Your Money by When You Need It
The most important step in a crisis is not choosing funds, it is sorting money into buckets so you never have to sell equity at a bad time.
| Bucket | Purpose | Where It Typically Sits |
|---|---|---|
| Emergency fund | 6 to 12 months of expenses for job loss, medical bills or disaster | Savings account, liquid funds, short fixed deposits |
| Short-term goals (0 to 3 years) | Down payment, tuition, weddings | Liquid, ultra-short or short-duration debt funds, fixed deposits |
| Medium-term goals (3 to 7 years) | Home, car, child’s education | Hybrid or balanced funds mixing equity and debt |
| Long-term goals (7+ years) | Retirement, wealth building | Diversified equity funds, index funds, some gold |
If your emergency fund and short-term goals are protected, a market fall is uncomfortable but not dangerous, because you are not forced to sell anything.
Step 2: Check Your Emergency Fund and Insurance First
Before worrying about the market, confirm you can survive three to six months without normal income. Check that your health insurance and term life cover are active and that premiums are not going to lapse. In a natural calamity, insurance and liquid cash matter far more than the state of your equity portfolio. Keep digital copies of policy documents, folio statements and ID proofs somewhere accessible, and make sure at least one family member knows where they are.
Step 3: Rebalance Instead of Reacting
Suppose your target is 60% equity and 40% debt. After a sharp fall, equity may shrink to 50% of your portfolio. Rebalancing means moving money back toward your target, which in practice means buying equity when it is cheap.
The tax-efficient way is to rebalance using fresh money first: direct new SIP contributions or extra savings to the underweight asset before selling anything, since selling triggers capital gains tax and possible exit load. A common rule of thumb is to rebalance once a year or when an asset class drifts more than about five percentage points from its target. Avoid rebalancing daily or reacting to every headline.
Step 4: Think About Balance Across Asset Classes
Equity. Stay diversified across large, mid and small caps or through broad index funds, and avoid concentrating in a single theme or sector because of a news story. In an oil shock, some sectors gain and others lose, and predicting which is rarely reliable.
Debt. When interest rates are expected to rise, longer-duration bond funds can fall in value, so short-duration and liquid funds are generally steadier for money you may need soon. Check a debt fund’s holdings and credit quality rather than chasing the highest yield.
Gold. Gold has often held up during geopolitical stress and has been trading at very high levels recently. Many planners suggest a modest allocation, commonly a small single-digit to low double-digit percentage, for diversification, but buying heavily after a large run-up carries its own risk.
Cash. Holding some cash or liquid funds gives you the option to invest more during a fall and protects you from forced selling.
What To Do If Markets Close or Redemptions Are Delayed
In rare situations, such as an unscheduled closure of markets, mutual fund rules allow a fund house to restrict or delay redemptions for a period. This is uncommon, but it is another reason to keep an emergency fund in bank accounts or liquid instruments you can access immediately, instead of relying on redeeming equity funds on short notice.
If a Natural Calamity or Personal Disaster Hits You
A flood, earthquake, cyclone or other calamity can affect your home, business or income, even if markets barely move. In that case:
Secure the essentials first: shelter, medical needs and insurance claims. File insurance claims promptly and keep documentation. Use your emergency fund before touching long-term investments. Talk to your bank and lenders early about EMI relief options if your income is disrupted, since lenders often have hardship or restructuring processes, and communicating early is better than missing payments and damaging your credit score. If you must reduce investing, pause or lower your SIPs rather than redeem long-term holdings or break tax-saving fund lock-ins, and remember that many fund houses do not allow reducing an existing SIP amount, so you may need to start a smaller new SIP after cancelling. Consider a loan against mutual funds only as a last resort, since it carries interest and risk if markets fall further.
Common Mistakes People Make in a Crisis
The most damaging mistake is stopping SIPs and redeeming near the bottom, which converts a temporary paper loss into a permanent one. Another is trying to time the exact low by holding cash and waiting, and then missing the recovery. Investors also chase whatever is rising, such as a hot sector or gold after a large rally, and end up buying high. Using leverage, borrowing to invest or trading in derivatives during volatile periods can turn a manageable fall into a disaster. Many people keep no emergency fund, so a single shock forces them to sell equity at the worst time. Others check their portfolio several times a day and make decisions based on fear. And crises attract scams, so be cautious of anyone promising guaranteed returns, “crash-proof” schemes or urgent investment opportunities.
A Simple Crisis Checklist
| Question | If Yes | If No |
|---|---|---|
| Do I have 6 to 12 months of expenses set aside? | Good; continue investing | Build this before adding to equity |
| Is any money I need within 3 years sitting in equity? | Move it to safer funds gradually | You are positioned sensibly |
| Is my income stable? | Continue SIPs | Prioritise cash, insurance and EMIs; pause or reduce SIPs |
| Has my equity share drifted far from target? | Rebalance with fresh money first | No action needed |
| Are my insurance policies active? | Confirm premiums are set to auto-pay | Fix this immediately |
| Am I making decisions from news alerts? | Step back and review your written plan | Stay the course |
My Take
The worst part of a crisis is that it feels like a decision point when it is usually a test of the plan you made earlier. Most of the decisions that determine how you fare, an adequate emergency fund, sensible asset allocation, no leverage and SIPs aimed at long-term goals, are made in calm markets, not during a war.
If you have those in place, the best action is often the most boring one: keep the SIP running, rebalance calmly once a year and avoid checking the market every hour. If you do not, use this moment to build them, without trying to fix everything at once. Start with the emergency fund and insurance, then look at whether any short-term money is sitting in equity. The market will do what it does, but a plan that survives a bad year is worth far more than a prediction that happens to be right.
Frequently Asked Questions
1. Should I stop my SIP during a war or market crash? If your goal is more than five years away and your income is stable, continuing is generally sensible because you buy more units at lower prices. Pause only if you need the cash for emergencies or your income is affected.
2. Is it a good time to increase my SIP when markets are falling? It can be, if you have surplus cash beyond your emergency fund and a long horizon. Consider staggering extra investment over several months instead of investing everything at once.
3. How long do markets take to recover after a crash? It varies. The 2020 COVID crash recovered in roughly eight months, while the 2008 crisis took around two years. Past recoveries do not guarantee future ones.
4. How much emergency fund should I keep? Most planners suggest six to twelve months of essential expenses, held in a savings account, liquid fund or short deposits so it is accessible immediately.
5. Is gold a safe investment during a war? Gold has often held up during geopolitical stress, but it is already trading at high levels and can fall too. A modest allocation for diversification is more sensible than a large bet.
6. What should I do with debt funds if interest rates may rise? Longer-duration bond funds can lose value when rates rise, so short-duration and liquid funds are generally steadier for money you may need soon. Check credit quality and holdings.
7. Should I redeem my mutual funds if I am worried about the market? Redeeming out of fear often locks in losses. Redeem only money you genuinely need, and consider exit loads and tax before selling.
8. What if I lose my job or my home is affected by a disaster? Use your emergency fund first, keep insurance and EMIs current, talk to lenders about relief early, and pause or reduce SIPs rather than breaking long-term investments.
9. How do I rebalance my portfolio after a fall? Redirect fresh SIP money and savings to the asset class that has fallen below target before selling anything, and rebalance about once a year or when an asset class drifts roughly five percentage points from its target.
10. Can a mutual fund stop me from redeeming during a crisis? In rare circumstances such as an unscheduled closure of markets, fund rules permit restrictions or delays on redemptions. Keep your emergency money in instruments you can access immediately.
Disclaimer
This article is for general informational and educational purposes only and does not constitute investment, tax or financial advice. Mutual fund investments are subject to market risks, and past performance is not indicative of future results. Market conditions described reflect reporting as of late September 2026 and can change quickly. Historical recovery figures are approximate. Readers should consider their own goals, risk tolerance and finances and consult a SEBI registered investment adviser before making decisions. FinanceChecks.com is not a SEBI registered investment adviser.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.