How To Track Every Investment You Own And Make Sure Your Family Knows Where To Find Them

A woman in Pune once spent almost a year after her father passed away trying to piece together what he actually owned. She knew he invested regularly because he talked about it often at family dinners, mentioning a mutual fund here, a fixed deposit there, a policy he had bought when she was born. What she did not have was a single piece of paper that told her where any of it actually was.
She found three bank passbooks in a drawer, none of which matched the fixed deposit receipts she eventually discovered in an old suitcase. She found one insurance policy document but suspected there were at least two more based on comments he had made over the years. She had no idea he held shares directly in a demat account until a dividend cheque, of all things, arrived at the house addressed to him nearly eight months after he had passed. She never did find out whether he had invested in the Sukanya Samriddhi scheme he once mentioned opening for her daughter, because by the time she thought to check properly, she had already spent so much energy chasing everything else that this one detail simply slipped through.
This story is not unusual. It is close to the default outcome for most Indian families, because most of us build our investment portfolios the same scattered way over a lifetime, a mutual fund here, a stock purchase there, an insurance policy bought because an agent visited during a wedding season, a post office scheme opened because a parent insisted on it, a fixed deposit renewed every year without much thought given to where the certificate physically lives. Nobody sits down and builds all of this on one platform, in one place, with one clear record. And because nobody does, the person left behind after an unfortunate event often has to reconstruct a financial life almost entirely from memory, old messages, and whatever documents happen to survive.
This article is about fixing exactly that problem, both for your own peace of mind while you are alive and actively managing your money, and for the people who would otherwise be left guessing after you are gone.
Quick Answer
Tracking a scattered investment portfolio across mutual funds, stocks, fixed deposits, post office schemes, insurance policies and government savings plans starts with three habits working together. First, use the free consolidated statements already available to you, a single mutual fund statement covering every fund house you have invested through, a single demat statement covering every share you hold, and your bank and post office passbooks for deposits. Second, build one simple master document listing every single investment by name, account or folio number, the institution holding it, and whether a nominee has actually been added, since nomination is the single fastest legal route your family has to access an asset after your death. Third, tell at least one trusted family member exactly where that master document lives, whether in a locked drawer, with a lawyer, or in a sealed envelope with a close relative, because a record nobody else can find is barely better than no record at all.
About This Guide
This guide has been researched and written by the FinanceChecks editorial team, drawing on the consolidated account statement frameworks maintained by mutual fund registrars, depository nomination rules under the Companies Act and SEBI regulations, the Investor Education and Protection Fund framework under Section 124 of the Companies Act 2013, and the Reserve Bank of India’s unclaimed deposit tracking initiative.
FinanceChecks is an independent Indian personal finance publication. We are not lawyers or licensed financial planners, and this guide is meant to help you organise your own financial records, not replace personalised legal or estate planning advice. Please read the disclaimer at the end of this guide.
Why This Problem Is So Common In India Specifically
Part of the reason this is such a widespread issue in Indian households comes down to how naturally our investment habits sprawl across unrelated platforms over the years. A person might have started a systematic investment plan through one mutual fund distributor a decade ago, opened a demat account with a different broker when trading apps became popular, kept renewing fixed deposits at whichever bank branch was closest to home at the time, bought a post office recurring deposit because a parent trusted the post office more than private banks, taken out a life insurance policy through an agent who visited during a family function, and opened a Public Provident Fund account at yet another bank entirely because that branch happened to offer better service.
None of these platforms talk to each other. Your mutual fund distributor has no idea you also hold fixed deposits at three different banks. Your insurance agent has no visibility into your Public Provident Fund balance. Each individual institution keeps a perfectly accurate record of exactly what you hold with them, but nowhere does a single, complete picture of your entire financial life exist, except inside your own head, and eventually, inside nobody’s head at all.
The Three Consolidated Statements That Do Most Of The Heavy Lifting
Before building anything from scratch, it is worth knowing that a meaningful chunk of this tracking problem already has a ready made solution sitting largely unused in most people’s inboxes.
- For mutual funds specifically, both major registrar and transfer agents in India, the ones that process transactions on behalf of nearly every mutual fund house in the country, offer what is called a consolidated account statement. This single document lists every mutual fund folio you hold across every fund house registered with either agency, using just your Permanent Account Number, regardless of how many different apps or distributors you used to actually make those investments. Requesting this statement takes a few minutes online and instantly solves the single most common blind spot in most people’s investment tracking, the mutual fund folio bought years ago through an app that has since been forgotten or deleted from a phone.
- For shares and other securities held in demat form, both depositories operating in India allow you to request a consolidated statement covering every demat account linked to your Permanent Account Number, even across multiple different stockbrokers. This is precisely the kind of document that would have told the woman in Pune about her father’s direct equity holdings months earlier than a stray dividend cheque eventually did.
- For bank fixed deposits and savings accounts, there is no single national consolidated statement the way there is for mutual funds and demat holdings, which is exactly why these tend to be the hardest category to track down after the fact. This makes your own manual record keeping considerably more important for this specific category than for mutual funds or shares, where at least a digital safety net already exists.
Building Your Own Master Investment Record
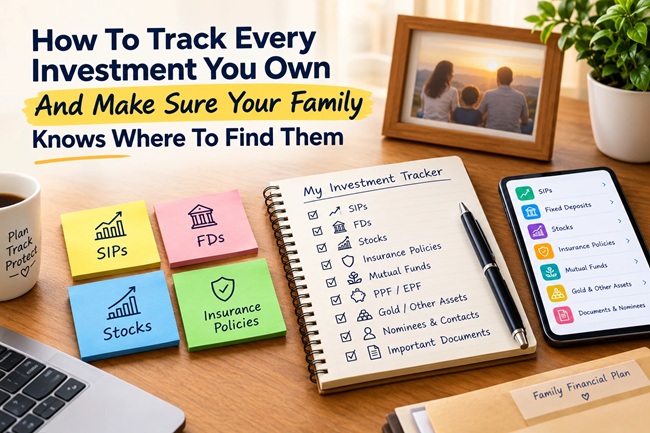
Once you have pulled these consolidated statements, the next step is building a single master document that brings every single financial holding into one place, regardless of category. This does not need to be anything elaborate. A simple spreadsheet or even a clearly organised handwritten notebook works perfectly well, as long as it is complete and kept reasonably current.
For every single personal investment you hold, the record should capture a handful of consistent details. The name of the specific investment or scheme. The institution or company holding it, whether that is a mutual fund house, a bank branch, a post office, an insurance company, or a stockbroker. The account, folio or policy number. Roughly when it matures or whether it is open ended. And critically, whether a nominee has actually been registered against that specific holding, since this single detail determines how smoothly, or how painfully, your family will eventually be able to access it.
This exercise is worth doing for every category without exception. Systematic investment plans and mutual fund folios. Direct equity holdings in your demat account. Every fixed deposit across every bank, since renewing a deposit each year without updating your own record is exactly how these quietly become forgotten. Post office schemes including recurring deposits, the National Savings Certificate, the Public Provident Fund if held through a post office rather than a bank, the Senior Citizens Savings Scheme, and the Sukanya Samriddhi Yojana if you have opened one for a daughter. Every life insurance policy, health insurance policy, and any standalone term plan. Your Employees Provident Fund balance and Universal Account Number. And any government savings bonds or sovereign gold bonds you may have subscribed to over the years.
Why Nomination Matters More Than Almost Anything Else On This List
If there is one single action that does more to protect your family than any spreadsheet, tracking app, or filing system, it is simply ensuring every single financial holding you own actually has a c registered against it, and that the nominee details are current rather than pointing to someone from decades ago whose relationship to you may have since changed entirely.
A registered nominee gives whoever you name a relatively direct, fast administrative path to claim an asset after your death, without needing to go through the far longer and more expensive process of obtaining a legal heir certificate or succession certificate through the courts, which becomes the fallback path whenever no nominee exists or the nomination has lapsed or was never updated. This is true across mutual funds, demat accounts, bank deposits, post office schemes, insurance policies and provident fund accounts alike, though the exact process for actually adding or updating a nominee differs slightly by institution.
It is worth being precise about something many people misunderstand here. A nominee is legally more of a trustee positioned to receive and hold an asset temporarily on behalf of the actual legal heirs, rather than automatically becoming the final, absolute owner of that asset in every single circumstance, particularly where a valid will exists that says otherwise. Despite that legal nuance, having a nominee registered still dramatically speeds up the practical process of a family actually accessing funds and paperwork in the difficult period immediately following a death, which is precisely why it matters so much even though it does not fully replace the need for a proper will.
Telling Your Family Where To Actually Find All Of This
A perfectly complete master record accomplishes almost nothing if the people who need it one day have no idea it exists or where to look for it. This is the step people skip most often, usually because talking openly about death and money in the same conversation feels uncomfortable, particularly within families where finances have traditionally been treated as a private, individually managed matter rather than something discussed openly across generations.
The practical fix does not require an elaborate family meeting about mortality. It simply requires telling at least one trusted person, a spouse, an adult child, a sibling, or in some cases a lawyer or a trusted family friend, exactly where your master investment record physically or digitally lives. This could be a specific drawer at home, a sealed envelope kept with a close relative, a document stored with your lawyer alongside your will, or a password protected file whose access details are shared separately with someone you trust. The specific method matters far less than the simple fact that at least one other person actually knows where to look, rather than having to search an entire house drawer by drawer the way the woman in Pune eventually had to.
It is worth pairing this master record with an actual will, or at minimum a clearly written letter of wishes, since a will governs how your assets are ultimately distributed in a way that complements, rather than replaces, the practical convenience that nominations provide.
What To Do If You Suspect A Family Member Left Behind Unclaimed Investments
If you find yourself on the other side of this problem, trying to trace investments a family member may have held without leaving behind clear records, several official channels exist specifically for this situation, and it is worth knowing about them before assuming an asset is simply lost forever.
For bank deposits and accounts that have gone dormant or unclaimed, the Reserve Bank of India runs a centralised portal specifically designed to help people search across participating banks using basic identifying details, without needing to already know which specific bank branch might be holding the account.
For shares and dividends, a specific rule under the Companies Act requires that if dividends on a shareholding go unclaimed for seven consecutive years in a row, both the unclaimed dividend amount and the underlying shares themselves get transferred into a fund called the Investor Education and Protection Fund, managed by the Ministry of Corporate Affairs. Importantly, there is no deadline for claiming these back. A legal heir or nominee can file a claim with the fund at any point, using a specific claim form, to recover both the shares and the accumulated dividend, provided they can establish their entitlement with appropriate documentation.
For mutual fund holdings, the same consolidated account statements mentioned earlier remain useful even after someone has passed away, since a legal heir or nominee with the deceased person’s Permanent Account Number details can generally request these statements to identify exactly which fund houses and folios need to be formally claimed or transmitted into the survivor’s name.
For insurance policies, if you are fairly confident a policy exists but cannot locate the actual document, most major insurance companies maintain their own unclaimed policy lookup facilities, and a formal death claim process can generally proceed even without the original physical policy document, provided the claimant can establish the policy’s existence and the policyholder’s identity through other means.
Common Mistakes People Make With Investment Tracking
- Assuming children or a spouse will simply figure it out later based on general awareness of your financial habits. General awareness that someone invests regularly is nowhere close to the same as knowing specific folio numbers, policy numbers, or which of several banks actually holds a particular fixed deposit.
- Updating a nominee on some accounts after a major life event, like marriage or the birth of a child, while forgetting to update it everywhere else. Nomination details drift out of date precisely because updating them requires actively remembering every single institution where you hold an investment, which is exactly the same organisational gap this entire article is trying to solve.
- Treating a verbal conversation about finances as equivalent to a written record. Memories fade, details get mixed up between similarly named schemes, and a conversation from years earlier is a considerably weaker foundation for a family member to act on during an already difficult period than a clearly written document.
- Keeping a master record but never telling anyone it exists or where it is kept. A complete, accurate record that nobody else can locate provides almost the same practical value as no record at all.
- Renewing fixed deposits year after year without updating a personal master list, since these are exactly the holdings most likely to be genuinely forgotten given the absence of any single consolidated statement covering deposits the way mutual funds and demat holdings already have.
- Assuming a will alone solves everything, without also ensuring nominations are current across individual accounts. A will determines eventual legal ownership, but nominations determine how quickly and smoothly a family can actually access funds and paperwork during the immediate aftermath, which is a genuinely different and equally important practical concern.
My Take
I think the deeper reason this problem persists across so many Indian families is not laziness or carelessness, it is that organising a complete financial record forces a certain kind of uncomfortable honesty about mortality that most of us would rather postpone indefinitely. Nobody particularly enjoys sitting down to write out exactly what would happen to their money if they were no longer around to manage it themselves. It is far easier to keep renewing fixed deposits, keep contributing to a systematic investment plan, and simply trust that everything will somehow sort itself out later, the same quiet assumption the father in that Pune household almost certainly made himself.
What I would push back on gently is the instinct to treat this as a one time task you complete and then forget about. A master investment record from three years ago that has not been updated since is only marginally more useful than no record at all, since it will almost certainly be missing whatever you have invested in more recently and may still list nominee details you meant to update after a change in family circumstances but never got around to. The genuinely useful version of this habit is treating your master record the same way you might treat an annual health checkup, a fixed, recurring appointment with yourself, ideally once a year, to update whatever has changed and confirm nominations are still accurate everywhere they need to be.
My honest, practical suggestion is to start considerably smaller than a perfect, exhaustive system. Even a single page listing just the institution names and account numbers for everything you currently hold, shared with one person you trust, immediately puts your family in a dramatically better position than the alternative of starting from nothing. Perfect organisation can come later. A starting point that actually exists and that someone else knows about is worth far more than an ideal system that only ever lives inside your own head.
Frequently Asked Questions
How can I check all the mutual funds I have invested in across different platforms?
Request a consolidated account statement from either of the two major mutual fund registrar and transfer agencies operating in India, using your Permanent Account Number. This single statement will list every mutual fund folio you hold across every fund house registered with that particular agency, regardless of which app or distributor you originally used to invest.
How do I find out about shares I might have forgotten I own?
Request a consolidated demat account statement from either depository using your Permanent Account Number, which will show every demat account and shareholding linked to your identity across different stockbrokers.
What happens to fixed deposits if nobody knows they exist after a death?
Unlike mutual funds and demat holdings, banks do not offer a single consolidated national statement for fixed deposits, which makes them considerably harder to trace without a personal record. Banks do eventually classify very old, genuinely unclaimed deposits as dormant, and the Reserve Bank of India’s centralised portal allows people to search for such unclaimed deposits and accounts across participating banks.
Why does nomination matter so much if I already have a will?
A registered nominee provides a considerably faster, simpler administrative path for a family member to claim an asset immediately after a death, without necessarily needing a legal heir certificate or succession certificate. A will, by contrast, governs the final legal distribution of your overall estate. The two work best together rather than as substitutes for one another.
What happens to shares if dividends go unclaimed for many years?
Under the Companies Act, if dividends on a shareholding remain unclaimed for seven consecutive years, both the unpaid dividend amount and the underlying shares themselves are transferred to the Investor Education and Protection Fund. There is no deadline for a legal heir or nominee to later file a claim to recover both the shares and the accumulated dividend.
Should I share my account passwords with a family member as part of this process?
Sharing login credentials carries its own security risks and is generally not recommended as a primary strategy. A safer approach is documenting which institutions you hold investments with and the relevant account or folio numbers, while keeping actual passwords and sensitive access details separately secured, such as with a lawyer or in a sealed document, to be accessed only when genuinely needed.
How often should I update my master investment record?
At minimum once a year, ideally timed around a natural checkpoint such as after filing your annual income tax return, when you are already reviewing your financial year as a whole. Any major life event, a new investment, a marriage, the birth of a child, or a change in your nominee preferences, is also a reasonable trigger to update the record immediately rather than waiting for the next annual review.
Can a nominee simply keep an asset for themselves instead of distributing it to legal heirs?
Generally, a nominee is meant to receive and hold an asset temporarily as a trustee on behalf of the rightful legal heirs, rather than automatically becoming its final, absolute owner in every circumstance, particularly if a valid will specifies a different distribution. This is exactly why having both a current nomination and a proper will matters, rather than relying on either one alone.
Where should I physically keep my master investment record and important documents?
Common, reasonably safe options include a locked drawer or safe at home, a bank locker, or safekeeping with a trusted lawyer alongside your will. What matters most is not the specific location itself, but ensuring at least one trusted family member actually knows where that location is.
Does the government have any single portal that shows all my investments in one place?
No single government portal currently consolidates every category of investment, mutual funds, shares, fixed deposits, insurance and post office schemes, into one unified view. Separate tools exist for specific categories, consolidated statements for mutual funds and demat holdings, the Reserve Bank of India’s portal for unclaimed bank deposits, and the Investor Education and Protection Fund for unclaimed shares and dividends, which is exactly why building your own personal master record across all categories remains genuinely necessary.
Disclaimer
The information provided in this article is for general educational and informational purposes only and should not be construed as financial, legal, or estate planning advice specific to your individual circumstances.
FinanceChecks is an independent personal finance publication and is not a registered investment adviser, law firm, or estate planning service. Processes for requesting consolidated statements, updating nominations, and claiming unclaimed assets can vary between institutions and may change over time due to regulatory updates. Please verify current procedures directly with your specific bank, mutual fund registrar, depository, insurance company, or post office branch before acting on the general guidance described here.
This article does not constitute legal advice regarding wills, succession, or estate planning. Please consult a qualified lawyer or financial planner for guidance specific to your family’s situation, particularly around drafting a will or structuring nominations to align with your actual intentions for asset distribution.
FinanceChecks and its authors accept no liability for any loss, delay, or difficulty arising from reliance on the information presented in this article.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.