How Do Investors Calculate a Startup’s Valuation? The Formulas, Metrics, and Math Explained Simply

Meera had never thought about her company’s “valuation” until an investor asked for her numbers over a Zoom call and said, “We’re thinking ₹15 crore pre-money.” She smiled, nodded, and said she’d get back to him — then spent the entire evening googling what “pre-money” even meant, and whether ₹15 crore was a fair number for a business doing ₹40 lakh a month in revenue.
If you’ve ever been in Meera’s position, you already know the strange part: valuation isn’t printed anywhere. There’s no invoice, no government rate card, no single formula that spits out one “correct” number. It’s a mix of math, market sentiment, and negotiation — and yet, once a number is agreed on, it decides how much of your own company you keep. This guide breaks down exactly how that number gets calculated, in plain language, with the actual formulas investors use and how you can estimate your own.
What “Valuation” Actually Means (Before the Formulas)
Before the math, three terms trip up almost everyone new to this:
- Pre-money valuation — what your company is worth before the new investment comes in.
- Post-money valuation — what it’s worth after the investment is added.
Post-money = Pre-money + Investment Amount. - Dilution — the percentage of your company you give up in exchange for that investment.
Dilution % = Investment Amount ÷ Post-money Valuation.
So if an investor puts in ₹1 crore at a ₹9 crore pre-money valuation, the post-money valuation is ₹10 crore, and the investor now owns 10% of your company. Every valuation method below is really just different ways of arriving at that pre-money number.
Why There’s No Single Formula For Valuation Calculation
A 20-year-old manufacturing company with steady profits can be valued using its actual cash flows — the numbers are known, predictable, and provable. A 6-month-old startup with no revenue yet has none of that. So the method investors use changes almost entirely based on your stage:
| Stage | What exists | Typical valuation approach |
|---|---|---|
| Idea/pre-revenue | Founders, a plan, maybe a prototype | Qualitative frameworks (Berkus, Scorecard) |
| Early revenue | Some paying customers, early growth | Revenue multiples, comparable deals |
| Growth stage | Predictable revenue, real metrics | VC Method, comparables, sometimes DCF |
| Mature/profitable | Stable cash flow, financial history | Discounted Cash Flow (DCF), earnings multiples |
Let’s go through each, in the order a founder actually encounters them.
Stage 1: Valuing a Startup With No Revenue Yet
If there’s no revenue, there’s nothing to multiply — so investors lean on structured, somewhat subjective frameworks that turn “does this look promising” into a number.
The Berkus Method
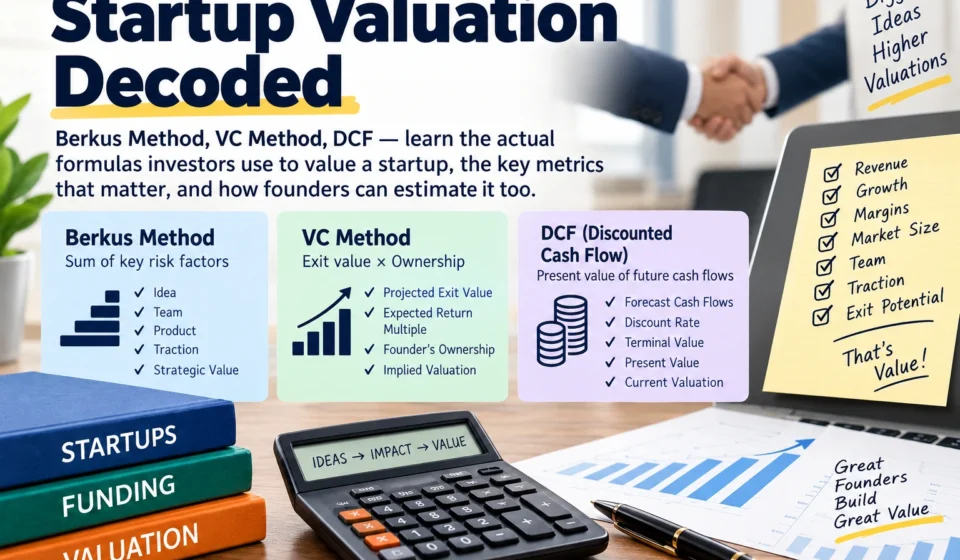
Investor Dave Berkus created this approach specifically for pre-revenue startups. It assigns a value (commonly up to $500,000 each, though investors adjust this to local markets) to five things that reduce risk, capped around $2.5 million pre-money in its original form:
- A sound business idea
- A working prototype (reduces technology risk)
- A strong founding/management team (reduces execution risk)
- Strategic relationships or early partnerships (reduces market risk)
- Product already launched or early sales (reduces production risk)
You essentially total up how much each factor is “worth” based on how derisked it makes the business, and that sum becomes your rough valuation.
The Scorecard Method
Here, you start with the average valuation of similar startups that recently raised money in your city, sector, and stage — pulled from sources like startup news coverage, Tracxn, or Crunchbase. Then you adjust that average up or down using weighted factors:
| Factor | Typical weight |
|---|---|
| Strength of the founding team | 0–30% |
| Size of the market opportunity | 0–25% |
| Product or technology | 0–15% |
| Competitive landscape | 0–10% |
| Marketing and sales channels | 0–10% |
| Need for additional funding | 0–5% |
| Other factors | 0–5% |
You compare your startup to the “average” comparable on each factor — better, worse, or in-line — and the weighted adjustment gives you a multiplier to apply to that average valuation.
Risk Factor Summation Method
Similar logic again: start from a comparable average valuation, then add or subtract a fixed amount (often around $250,000 per factor) across roughly 12 risk categories — management risk, stage of business, legislative/political risk, manufacturing risk, sales/marketing risk, funding risk, competition risk, technology risk, litigation risk, international exposure, reputation risk, and exit potential.
Notice the pattern across all three: anchor to a real comparable, then adjust for how your specific startup is more or less risky. That’s the underlying logic even when there’s no revenue to build a clean formula around.
You May Also Like To Read About:
- 10 Legal Mistakes First-Time Founders Make (and How to Avoid Them)
- How to Register a Startup in India: OPC vs Pvt Ltd vs LLP Explained
- Government Schemes for Women Entrepreneurs in India: The Complete 2026 Guide to Loans, Subsidies and Support
- CGSS Explained: How the Government Is Backing ₹20 Crore Startup Loans Without a Single Rupee of Collateral
- PMEGP (Prime Minister Employment Generation Program) Explained: How the Government Is Quietly Funding Thousands of First-Time Entrepreneurs Every Month
- DPIIT Recognition: The One Government Certificate Every Indian Startup Needs Before Anything Else
- Startup India Seed Fund Scheme (SISFS): The Complete Guide Every Indian Founder Should Read Before Applying
- Government Schemes for Startups and Small Businesses in India: The Complete 2026 Guide to Funding, Tax Breaks and Ease of Doing Business
Stage 2: Valuing a Startup With Revenue
Once there’s real revenue, the math gets more concrete.
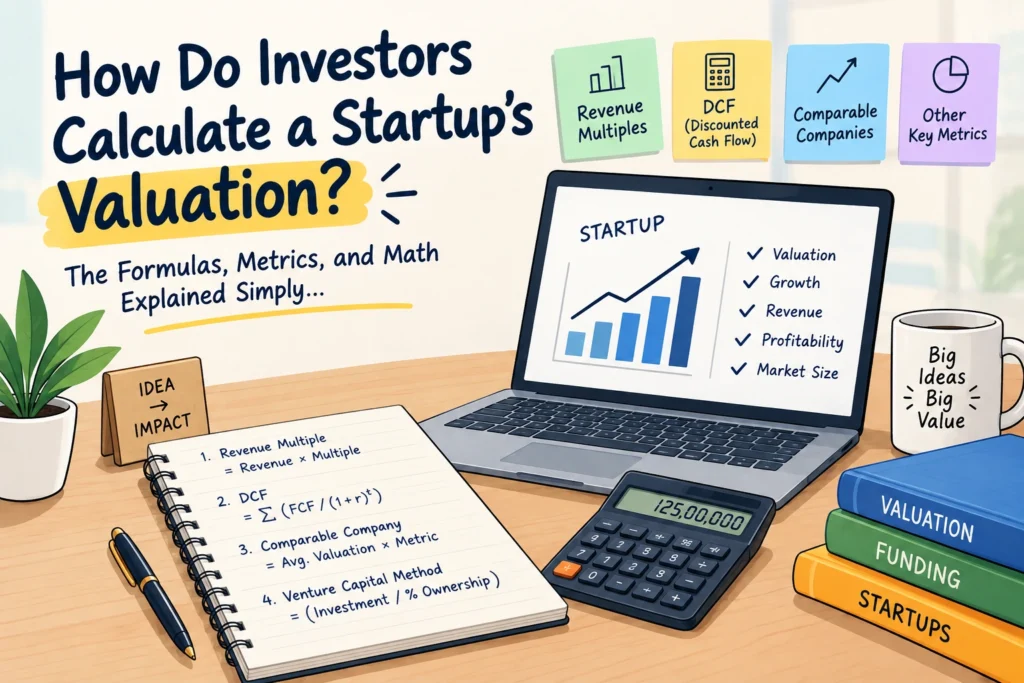
Revenue Multiple Method
This is the most commonly used method for early-revenue startups, and it’s simple:
Valuation = Annual Recurring Revenue (ARR) × MultipleThe “multiple” isn’t invented — it comes from what similar companies have recently sold or raised at. For Indian SaaS startups, multiples have typically ranged from 5x to 15x ARR depending on growth rate and margins; for marketplaces, services, or lower-margin businesses, multiples are usually much lower, often 1x–4x revenue. A high-growth SaaS company growing 3x year-over-year with 80% gross margins will command a very different multiple than a slow-growing services business with 20% margins — same “revenue,” very different valuation.
The Venture Capital Method
This is arguably the most important one to understand, because it’s how institutional investors actually think, even when they don’t say it out loud. Instead of asking “what is this company worth today,” they ask “what return do I need, and what does that imply about today’s price.”
Terminal Value = Exit Year Revenue × Exit Multiple
Post-Money Valuation (today) = Terminal Value ÷ Expected Return Multiple
Pre-Money Valuation = Post-Money Valuation − Investment Amount
Dilution % = Investment Amount ÷ Post-Money Valuation
Worked example: Suppose an investor believes your company will hit ₹100 crore in annual revenue five years from now, and similar companies exit (get acquired or go public) at around 4x revenue. That gives a terminal value of ₹400 crore. If the investor wants a 10x return on their money over that period (fairly typical for early-stage risk), they work backward: ₹400 crore ÷ 10 = ₹40 crore is what the company needs to be worth today (post-money) for their math to work. If they’re investing ₹4 crore, that’s exactly 10% of ₹40 crore — so pre-money valuation is ₹36 crore, and you’ve given up 10% of your company.
This is exactly why VC-offered valuations sometimes feel disconnected from a founder’s own sense of “what the business is worth” — the investor isn’t pricing today’s balance sheet, they’re pricing today’s stake against a future return they need to hit.
Discounted Cash Flow (DCF)
Used far more for later-stage or profitable companies with predictable cash flows than for early startups, since it needs reliable forecasts:
Value = Σ [Free Cash Flow in year t ÷ (1 + discount rate)^t] + Terminal Value ÷ (1 + discount rate)^nIn plain English: it adds up all the cash the business is expected to generate in future years, discounts each year’s cash back to today’s value (because ₹1 crore five years from now is worth less than ₹1 crore today), and adds a terminal value for everything beyond the forecast period. The “discount rate” reflects how risky those future cash flows are — riskier businesses get discounted more heavily.
Comparable Company Analysis (“Comps”)
This takes valuation multiples — Enterprise Value ÷ Revenue, Enterprise Value ÷ EBITDA, Price ÷ Earnings — from similar public or recently-funded private companies, and applies them to your own numbers. It’s really the same math as the revenue multiple method, just built on a more formal peer group rather than a single comparable deal.
Don’t Miss The Latest Updates On Startups and Entrepreneurship, Follow us on Youtube and Instagram.
The Metrics That Actually Move Your Multiple
Regardless of which formula gets used, these are the underlying numbers investors dig into, because they explain why one company gets 15x revenue and another gets 3x:
- ARR/MRR and growth rate — Annual/Monthly Recurring Revenue, and how fast it’s growing month-over-month and year-over-year. Growth rate often matters more to the multiple than the absolute revenue number.
- Gross margin — the percentage of revenue left after direct costs of delivering your product/service. Higher-margin businesses reliably command higher multiples.
- CAC (Customer Acquisition Cost) = total sales & marketing spend ÷ number of new customers acquired.
- LTV (Customer Lifetime Value) = average revenue per customer × gross margin % × average customer lifespan.
- LTV:CAC ratio — a ratio of 3:1 or higher is generally considered healthy; below 1:1 means you’re spending more to acquire a customer than they’re worth.
- Churn rate and Net Revenue Retention (NRR) — NRR above 100% means your existing customers are spending more over time even before counting new customers, which is one of the strongest signals investors look for.
- Burn rate and runway — how much cash you’re spending each month, and how many months of cash you have left at that rate.
- Rule of 40 — a common SaaS heuristic:
Growth rate % + Profit margin % should be ≥ 40. A company growing 60% but losing money can still pass; a company growing only 10% needs strong profitability to compensate. - TAM, SAM, SOM — Total Addressable Market, Serviceable Addressable Market, and Serviceable Obtainable Market, used to justify how large the business could realistically become, which underpins the multiple an investor is willing to pay.
How Founders Can Estimate Their Own Valuation (Without a Finance Degree)
You’re not expected to run a formal DCF model on a two-year-old startup — but you can triangulate a reasonable number using the same logic investors use:
- Find real comparables. Look up recent funding rounds in your sector, city, and stage — startup news coverage, Tracxn, or Crunchbase often report both the amount raised and the percentage stake sold, which lets you back into the valuation (
Investment ÷ Stake % = Post-money). - Apply a revenue multiple from those comparables to your own ARR, adjusting up or down based on whether your growth rate and margins are stronger or weaker than theirs.
- Sanity-check with the VC Method. If you have a realistic 5-year revenue projection and a sense of the return multiple investors at your stage typically expect (often 10x+ for seed, 3–5x for growth rounds), you can work backward to see what valuation today would need to be for their math to make sense.
- Adjust qualitatively, the way the Scorecard and Risk Factor methods do — is your team stronger or weaker than the comparable? Is competition heavier? Is the market bigger or smaller?
A useful gut-check for any term sheet: the numbers should reconcile cleanly as Post-money = Pre-money + Investment, and Dilution % = Investment ÷ Post-money. If those don’t line up, or if the percentage being asked for doesn’t match the stated valuation, that’s worth questioning before signing anything.
A Word of Caution on Multiples
Valuation multiples move with market sentiment far more than founders expect — the same SaaS company might be valued at 15x ARR during a hot funding cycle and 6x ARR during a cautious one, with no real change in the underlying business. Founders who anchor their expectations to peak-cycle valuations from a couple of years ago are often the ones most caught off guard by a “down round” later. Valuation is a snapshot of market conditions and investor appetite at a specific moment — not a permanent verdict on what your company is worth.
Frequently Asked Questions
1. What’s the difference between valuation and net worth?
Net worth (or book value) is based on a company’s assets minus liabilities on its balance sheet — a historical, accounting-based number. Valuation is forward-looking and reflects what someone is willing to pay today based on expected future growth and returns, which is why a loss-making startup can still have a valuation in the crores.
2. Why do two investors offer different valuations for the same startup?
Because valuation depends on assumptions — expected exit multiple, required return, growth projections, and how each investor weighs qualitative risk factors like team strength or competition. Two investors can look at identical numbers and reach different conclusions simply by plugging in different assumptions into the same formulas.
3. Is a higher valuation always better for founders?
Not necessarily. A very high valuation today (“priced to perfection”) can make it harder to raise your next round at an even higher valuation if growth doesn’t keep pace — leading to a “down round,” which can hurt morale, cap tables, and future fundraising. Many experienced founders prefer a fair, defensible valuation over the highest possible number.
4. What is a “down round” and why does it happen?
A down round is when a startup raises money at a lower valuation than its previous round — usually because growth slowed, market multiples compressed, or the previous valuation was too aggressive relative to actual performance. It’s directly connected to the multiples discussed above: if comparable company multiples fall industry-wide, even a growing company’s valuation can drop.
5. How does equity dilution work across multiple funding rounds?
Each new round issues new shares, which reduces the percentage owned by existing shareholders (though not necessarily the value of their stake, if the valuation has grown enough to offset the dilution). A founder who owns 100% pre-seed might own 70% after seed, 55% after Series A, and so on — dilution is normal and expected, which is why the percentage matters less than the value of that percentage over time.
6. Do these formulas apply the same way outside the startup/tech world?
The underlying logic (comparables, cash flow discounting, multiples) applies broadly to business valuation in general — small businesses, franchises, even real estate use variations of these methods. Early-stage frameworks like Berkus and Scorecard, however, were built specifically for pre-revenue startups and aren’t typically used outside that context.
7. What documents should founders prepare before a valuation conversation with investors?
At minimum: a cap table showing current ownership, monthly financials (revenue, expenses, burn rate), key metrics (CAC, LTV, churn, growth rate), and a realistic 3–5 year projection. Investors will ask for these regardless of stage, and having them ready signals preparedness — which itself can influence how an investor perceives risk (and therefore, valuation).
8. Can a startup be overvalued, and what happens then?
Yes — this happens when a valuation is based on optimistic projections that don’t materialize, or when market sentiment shifts after the round closes. The consequences show up later: difficulty raising the next round without a down round, pressure on the cap table, and sometimes down-stream effects on employee stock options, which are typically priced relative to the company’s valuation.
9. How often should a startup get formally valued?
There’s no fixed schedule — valuation typically happens whenever there’s a triggering event: a funding round, an ESOP pool creation (which often requires a 409A-style or fair market value assessment), an acquisition conversation, or annual compliance requirements in some jurisdictions. Outside of these events, most founders track their metrics rather than a formal valuation number.
10. Is there a single “correct” valuation for a startup at any given moment?
No — valuation is inherently a negotiated estimate, not an objective fact, which is exactly why multiple credible methods exist and can produce different numbers for the same company. What matters more than finding a single “right” number is being able to defend your number with real metrics, credible comparables, and a reasonable growth story.
About This Guide
This article draws on standard valuation frameworks used across venture capital and startup finance — including methods developed by early-stage investors like Dave Berkus, and standard corporate finance approaches (DCF, comparable company analysis) applied by financial analysts and institutional investors. It’s written to help founders and first-time entrepreneurs understand the reasoning behind a number they’ll otherwise only see appear in a term sheet.
Disclaimer: This article is for general informational and educational purposes only and does not constitute financial, investment, legal, or professional advice. Valuation methods, market multiples, and typical return expectations vary by sector, geography, and market conditions, and change over time. Founders and investors should consult a qualified financial advisor, chartered accountant, or investment banker before relying on any valuation for fundraising, investment, or legal decisions.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.