
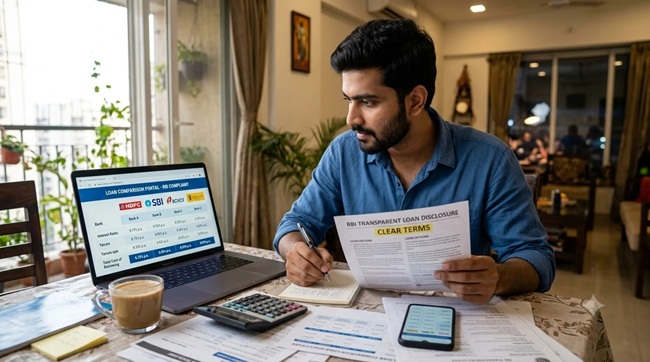
RBI’s New Framework to Ease Loan Comparisons: How Does Transparency Actually Benefit You?

Arjun once compared two personal loan offers the way most people do, by looking at the interest rate printed in bold on each bank’s website. One quoted 12%, the other 12.5%, so he went with the lower number without a second thought. What he didn’t factor in was a 2% processing fee buried in the fine print of the “cheaper” loan, plus a documentation charge the other lender didn’t have at all. By the time all the actual costs were added up, the loan with the “higher” headline rate would have genuinely cost him less over three years. He found this out only after signing, from a friend who happened to glance at his loan papers.
This exact kind of confusion, comparing loans on the one number lenders love to advertise while missing everything else stitched into the actual cost, is precisely what the RBI’s newest transparency framework was built to fix. Here’s what actually changed, and more importantly, how you can use it the next time you’re shopping for a loan.
Quick answer: RBI now mandates that every bank, NBFC, and digital lender give retail and MSME borrowers a standardized, one-page document called the Key Fact Statement, or KFS, before any loan agreement is signed. This document must disclose the loan’s Annual Percentage Rate, or APR, a single all-inclusive cost figure that folds in the interest rate plus every unavoidable fee, in addition to the EMI schedule, all charges, and foreclosure terms, in the borrower’s own language. This lets you compare loan offers on one true, comparable number instead of being misled by an attractively low headline interest rate that hides its real cost elsewhere.
Why This Rule Exists in the First Place
For years, comparing loan offers in India meant comparing whatever number a lender chose to put in the largest font on their website or application form, almost always the base interest rate. What that headline number conveniently left out varied wildly from lender to lender: processing fees, documentation charges, administrative costs, insurance bundled in without much explanation, and foreclosure penalties that only became relevant much later. Two loans with identical headline rates could end up costing meaningfully different amounts once all these pieces were added up, and borrowers had no simple, standardized way to see that difference before signing.
RBI first flagged this problem formally in its Statement on Developmental and Regulatory Policies in February 2024, and followed up with detailed guidelines in April 2024, aimed specifically at harmonizing how every regulated lender discloses this information. The rule became fully mandatory from 1 October 2024 for all new retail and MSME term loans, including fresh loans extended to existing customers, and the framework has continued to be reinforced through 2025 and into 2026, most recently through RBI’s Digital Lending Directions, which specifically tightened rules for loan apps and digital lenders effective 1 January 2026.
What a Key Fact Statement Actually Is
A KFS is a standardized, typically single-page document every lender is now required to hand you before you sign any loan agreement, not buried somewhere inside a lengthy contract, but presented clearly and separately, in a language you actually understand. It’s built to answer the exact questions a borrower genuinely cares about: how much am I borrowing, for how long, at what real cost, and what happens if I want to exit early.
Every KFS must include the sanctioned loan amount and tenure, the interest rate, whether fixed or floating, the Annual Percentage Rate covering the true all-in cost, a complete breakdown of every applicable fee, the EMI amount and full repayment schedule, and details of foreclosure or prepayment charges. It also has to include contact details for the lender’s grievance redressal officer, so you know exactly who to approach if something goes wrong later.
Two structural details make this genuinely stronger than earlier disclosure attempts. First, the KFS has to be shared with you and formally acknowledged before the actual loan agreement is even sent to you, meaning it can’t just be one page tucked inside a stack of paperwork you’re signing all at once. Second, lenders are now expected to honour the terms disclosed in the KFS during a defined validity window, which meaningfully reduces the risk of a lender quietly changing terms between the quote you were shown and the loan you actually receive.
You May Also Like To Read About:
- Buy Now, Pay Later: How It Actually Works, and Is It Secretly an EMI Trap?
- Claiming Both HRA Exemption and Home Loan Interest Deduction: Know When It’s Allowed — and When It’s Not
- What Actually Happens If You Default on a Loan in India
- Home Loan Prepayment vs Investing: When Should You Use Extra Cash to Repay Debt?
- Car Loan vs Personal Loan for Buying a Vehicle: The Real Cost Comparison
- Credit Card Minimum Due Trap: Why Paying Only That Amount Costs You Lakhs
APR: The Single Number That Actually Matters
If there’s one concept from this entire framework worth genuinely internalizing, it’s this: stop comparing interest rates, start comparing APR. The Annual Percentage Rate is a cash-flow-based calculation that combines your nominal interest rate with processing fees, documentation charges, and any other cost you cannot reasonably avoid as part of taking the loan, expressed as a single annualised percentage. It deliberately excludes genuinely optional add-ons, like insurance you’re free to decline, along with penalty charges and any third-party fees you negotiate separately, since those aren’t really part of the loan’s core, unavoidable cost.
This is exactly the gap that caught Arjun out. His two loan offers looked nearly identical on interest rate alone, but once processing fees and documentation charges were folded into a proper APR calculation, the picture flipped entirely. As of 2026, personal loan interest rates across Indian lenders range broadly from around 9.5% to 24% per annum, and without APR-based comparison, that headline range alone tells you almost nothing reliable about which specific offer is actually cheaper for your situation.
How This Actually Benefits You as a Borrower
The most direct benefit is finally being able to make a genuine apples-to-apples comparison across lenders. Whether you’re looking at a loan from a large public sector bank, a private bank, or an NBFC, every KFS now follows the same standardized format with the same required disclosures, which means you can, for the first time, meaningfully hold two loan offers side by side and know you’re comparing the same things.
There’s also a real protective effect built into the requirement that the KFS be presented in your own preferred language, rather than dense financial or legal English that many borrowers previously signed without fully understanding. Complex terms like foreclosure charges, penal interest structures, and recovery agent clauses are now expected to be explained in plain, accessible language before you commit to anything.
The mandatory grievance officer contact detail is another underrated benefit. If a lender doesn’t honour what was disclosed in your KFS, you now have a clear, documented first point of escalation, and if that doesn’t resolve things within 30 days, you can take the matter to the RBI Ombudsman directly, a path that’s considerably harder to pursue if you never had clear documentation of what was originally promised.
How to Actually Use Your KFS When Comparing Loans
When a loan offer lands in front of you, resist the instinct to look only at the interest rate box and move on. Find the APR figure specifically, since that’s the number genuinely comparable across different lenders, and use it, not the base interest rate, as your primary comparison point when weighing multiple offers.
Next, check the full fee breakdown line by line rather than assuming “processing fee” means the same modest amount across every lender, since these can vary considerably and materially affect your total cost, especially on larger loans. Pay close attention to the foreclosure and prepayment terms too, particularly if there’s any realistic chance you might want to repay the loan early, since a marginally higher APR paired with genuinely low or zero foreclosure charges can sometimes work out cheaper overall than a lower APR locked behind a steep prepayment penalty.
Finally, hold onto your KFS document even after the loan is disbursed. It’s your reference point if a dispute ever arises about what was actually promised versus what you’re later being charged, and it’s the document you’d need on hand if you ever have to escalate a complaint to your lender’s grievance officer or the RBI Ombudsman.
Who This Framework Actually Covers
The KFS mandate applies broadly across the lending landscape, commercial banks, both public and private, foreign banks operating in India, urban and state co-operative banks, NBFCs, and digital lending platforms, covering retail loans like personal loans, home loans, and vehicle loans, as well as MSME term loans. One notable exception worth knowing is credit card receivables, which are explicitly excluded from the KFS mandate, since credit cards already operate under a separate, established disclosure framework of their own.
For digital lending specifically, RBI’s more recent Digital Lending Directions have added further weight to this framework, including requirements around registering lending apps and stronger real-time credit disclosure, aimed squarely at cleaning up the digital and app-based lending space, where mis-selling and hidden charges have historically been a particularly persistent problem.
Common Mistakes Borrowers Still Make, Even With the KFS in Hand
The most frequent mistake, even now, is glancing only at the interest rate and the monthly EMI figure, and skipping past the APR and fee breakdown entirely, precisely the habit that led Arjun to nearly choose the more expensive loan. The KFS only helps if you actually read the specific line that matters most.
Another common mistake is not comparing foreclosure and prepayment terms carefully, focusing purely on the borrowing cost while ignoring the exit cost, which can matter just as much if your financial situation changes and you want to close the loan ahead of schedule.
A third mistake is signing a loan agreement without insisting on receiving and reviewing the KFS first, particularly with smaller digital lenders or loan apps, where the pressure to complete an application quickly can lead borrowers to skip a step that RBI has specifically mandated must happen before the loan agreement itself is even presented.
My Take
This is genuinely one of the more borrower-friendly regulatory changes RBI has pushed through in recent years, precisely because it doesn’t just create more paperwork, it standardizes the one thing that actually matters for comparison, the true cost of borrowing, into a single number every lender now has to disclose the same way. That said, transparency only protects you if you actually use it. A KFS sitting unread in your inbox does exactly nothing for you. The genuinely useful habit to build here is simple: the moment a loan offer arrives, find the APR line before you look at anything else, and treat that number, not the advertised interest rate, as the one you’re actually comparing across lenders.
Frequently Asked Questions
What is a Key Fact Statement (KFS)? A KFS is a standardized, typically one-page document that RBI-regulated lenders must provide to retail and MSME borrowers before signing a loan agreement, disclosing the loan amount, tenure, interest rate, APR, complete fee breakdown, EMI schedule, and foreclosure terms in the borrower’s preferred language.
When did RBI’s KFS rules become mandatory? The rules became fully mandatory from 1 October 2024 for all new retail and MSME term loans, including fresh loans to existing customers, following RBI’s guidelines issued on 15 April 2024. The framework was further strengthened through RBI’s Digital Lending Directions effective 1 January 2026.
What is APR and how is it different from the interest rate? APR, or Annual Percentage Rate, is an all-inclusive cost figure combining the nominal interest rate with unavoidable fees like processing and documentation charges, expressed as a single annualised percentage. The interest rate alone only reflects the base borrowing cost and excludes these additional charges, which is why comparing loans on interest rate alone can be misleading.
Does the KFS apply to credit cards? No. Credit card receivables are explicitly excluded from the KFS mandate, since credit cards operate under their own separate, pre-existing disclosure framework.
Which lenders are required to provide a KFS? The requirement applies to commercial banks, co-operative banks, NBFCs, and digital lending platforms offering retail or MSME term loans. This includes public sector banks, private banks, foreign banks operating in India, and registered digital lending apps.
What should I do if a lender doesn’t honour the terms disclosed in my KFS? You can first raise the issue with your lender’s grievance redressal officer, whose contact details are required to be included in the KFS itself. If the issue isn’t resolved within 30 days, you can escalate the complaint to the RBI Ombudsman through cms.rbi.org.in.
Should I compare loans based on interest rate or APR? APR is the more reliable figure for comparison, since it accounts for the interest rate plus unavoidable fees, giving a true picture of the total cost of borrowing. Two loans with similar interest rates can have meaningfully different APRs once fees are factored in.
Is insurance included in the APR calculation? No. Optional insurance that the borrower is free to decline is excluded from the APR calculation, along with penalty charges and separately negotiated third-party fees, since APR is meant to reflect only the unavoidable cost of the loan itself.
Can a lender change loan terms after issuing the KFS? Lenders are expected to honour the terms disclosed in the KFS during a specified validity window, which reduces the risk of terms changing between the initial quote and the final loan agreement. This validity period is itself disclosed within the KFS document.
Do I need to keep my KFS document after taking the loan? Yes. It’s advisable to retain your KFS even after the loan is disbursed, since it serves as your reference point for the originally disclosed terms and is useful documentation if you ever need to raise a dispute or escalate a complaint to your lender or the RBI Ombudsman.
Disclaimer: This article is for general informational and educational purposes only and does not constitute financial or legal advice. Loan terms, interest rates, and regulatory requirements are subject to change. Please review your specific Key Fact Statement carefully and consult your lender or a qualified financial advisor before finalizing any loan.

Shuchi founded Finance Checks after spending 16+ years working in corporate, managing operations and distribution. She managed her own finances, learned and read regularly and helped people make sense of their savings, loans, insurance, and investments.
She started this site to offer the kind of clear, honest financial guidance she wished was more available when she was learning to manage her own money. Every article is researched personally, checked against official sources such as the Reserve Bank of India, SEBI, or the Income Tax Department, and revisited whenever regulations or figures change. She is upfront about how the site earns money through ads and select affiliate partnerships, and she does not let either influence what she actually recommends to readers.

[…] RBI’s New Framework to Ease Loan Comparisons: How Does Transparency Actually Benefit You? […]